November 3, 2026
Our regime read changes today: RED, risk-off posture. Monday’s sell-off lifted spot volatility above 21, and the shape of the volatility curve got worse, not better. The November contract is still priced above the December contract, and the gap widened. With an election, a jobs report, and a major earnings week all landing in the same window, this is a day to protect principal first and let the repricing happen before adding risk.
Monday’s tape closed lower in the two tech-heavy indexes. The S&P 500 finished at 7,541.40, down 0.51 percent, the Nasdaq Composite fell 1.07 percent to 25,164.32, and the Dow rose 0.41 percent to 51,983.98, the only major index to gain. This morning futures are mixed: S&P 500 futures are down about 0.1 percent, Nasdaq 100 futures are up about 0.3 percent in a tentative bounce, and Dow futures are down about 0.8 percent. That mix, after a Monday drop that put the Nasdaq 100 into correction, more than 10 percent below its all-time closing high, reads as unsettled, not as a turn.
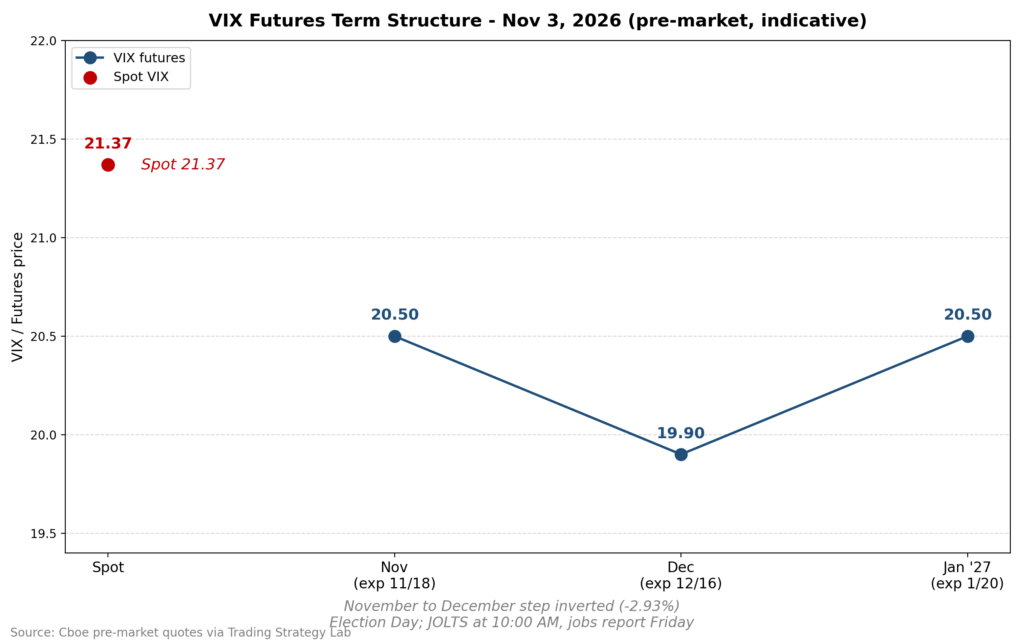
Spot VIX sits at 21.37 this morning, up from Monday’s close of 21.15, which itself rose 1.73 points on Monday. The November contract sits at 20.50 and the December contract at 19.90, so the market is still paying more for November volatility than for December. That gap of minus 0.60 points, or minus 2.93 percent, is more deeply inverted than Monday’s picture, and it sits far below the long term median gap of about 6.3 percent. In plain terms, traders are paying up for the event cluster inside the November window, today’s midterm elections, the November 6 payrolls report, and the November 10 CPI report, and pricing the December step below it. There is no cushion underneath this morning: the November contract sits 0.87 points below spot, so spot volatility is already above what the November contract is pricing. The January contract sits at 20.50, the same as November, so the total slope from spot to January is minus 0.87 points. The curve is essentially flat to slightly downward from spot to January, not upward sloping.
Positioning gives the same caution in plain terms. One Monday close snapshot puts spot at 7,541 below a flip level near 7,725 and just above a put wall near 7,500, a setup in which dealer hedging can amplify moves in either direction. A second Monday snapshot puts the flip near 7,653, with a put wall also near 7,500. When two methods disagree this plainly on the flip level, the plain read is to treat positioning as unsettled, not settled, while noting that both put spot below the flip and both put the put wall at 7,500. The expected daily move for the S&P 500 is about plus or minus 1.35 percent.
Two other pressures are worth watching. The 10 year Treasury yield sits about 4.925 percent this morning, up about 3 basis points and still below the 5 percent round number. Oil is giving back only a small part of Monday’s sharp fall, on US-Iran diplomacy hopes: West Texas crude is about 97.20 dollars this morning, up about 0.7 percent after Monday’s 7.1 percent fall to about 96.72 dollars, and Brent crude is about 105.10 dollars, up about 0.25 percent after Monday’s 7.6 percent fall to 104.82 dollars. Gold is near 3,900 dollars this morning, down more than 1 percent, and the dollar index is about 101.74, little moved.
Market news this morning, with no position framing, is led by earnings. Apple fell about 4 to 4.5 percent premarket after guiding holiday-quarter gross margin to 45 to 46 percent, against about 46.9 percent expected, and warning memory-chip costs will keep rising. Palantir also slid premarket despite a better-than-expected report. Shopify fell about 16 percent premarket after third-quarter revenue of 3.74 billion dollars matched consensus. AMD gained about 2.8 percent premarket ahead of its report after the close, with Amgen, Arista, and Booking also due after the close and Pfizer due before the open. Voters choose all 435 House seats and 35 Senate seats today, and prediction markets put Democrats at about a 75 percent chance of gaining Senate control.
The December question will not go away. The Fed target range was held at 3.75 to 4.00 percent on October 28 on a 10 to 2 vote, with Governor Cook and Cleveland Fed President Hammack dissenting in favor of an immediate hike. The next meeting is December 8 to 9. Futures and prediction markets put a December hike at roughly 73 to 79 percent, which still prices a hike as the base case, not as a coin flip. For a December hike to be taken off the table, inflation needs to keep cooling, and the next tests are Friday’s payrolls report and the November 10 CPI report.
What is next: there is no 8:30 AM release today, so there is no early print to react to this morning. The first US data arrive at 10:00 AM with JOLTS job openings for September, consensus about 7.10 to 7.16 million against a prior 7.079 million, and factory orders for September, consensus up 1.2 percent against a prior up 0.1 percent. Tonight brings election results. The week ahead then runs through ADP employment and ISM services on Wednesday, jobless claims on Thursday, and the October employment report on Friday, with payrolls expected up 50,000 to 65,000 after September’s 29,000 and unemployment at 4.2 percent.
What changes the read: the November to December gap widening materially toward a healthy slope, or spot volatility settling and holding lower with real cushion rebuilding underneath it. Until one of those happens, we stay risk-off and patient, with no hurry to add risk into an election, a jobs report, and a heavy earnings week.
Educational market analysis only. Not investment advice. See Terms of Use.
Leave a Reply