November 5, 2026
Our regime read is unchanged: AMBER, continue defensive posture. Wednesday’s relief rally held this morning after a clean beat on the 8:30 data, but the volatility curve is still almost flat at the front, so the market is paying almost nothing for that relief. Strict stops on existing credit spreads, trim speculative positions, and do not chase on margin. One bad headline ahead of Friday’s payrolls report could push spot volatility back above 20 again.
Wednesday’s tape closed strong. The S&P 500 finished at 7,688.62, up 1.58 percent, the Nasdaq Composite rose 1.44 percent to 25,736.51, and the Dow jumped 3.03 percent to 53,356.12, a gain of 1,569 points. This morning futures are holding the gains rather than extending them: S&P 500 futures are up about 0.12 percent, Dow futures are up about 0.70 percent, and Nasdaq 100 futures are down about 0.78 percent as chip stocks sell off.
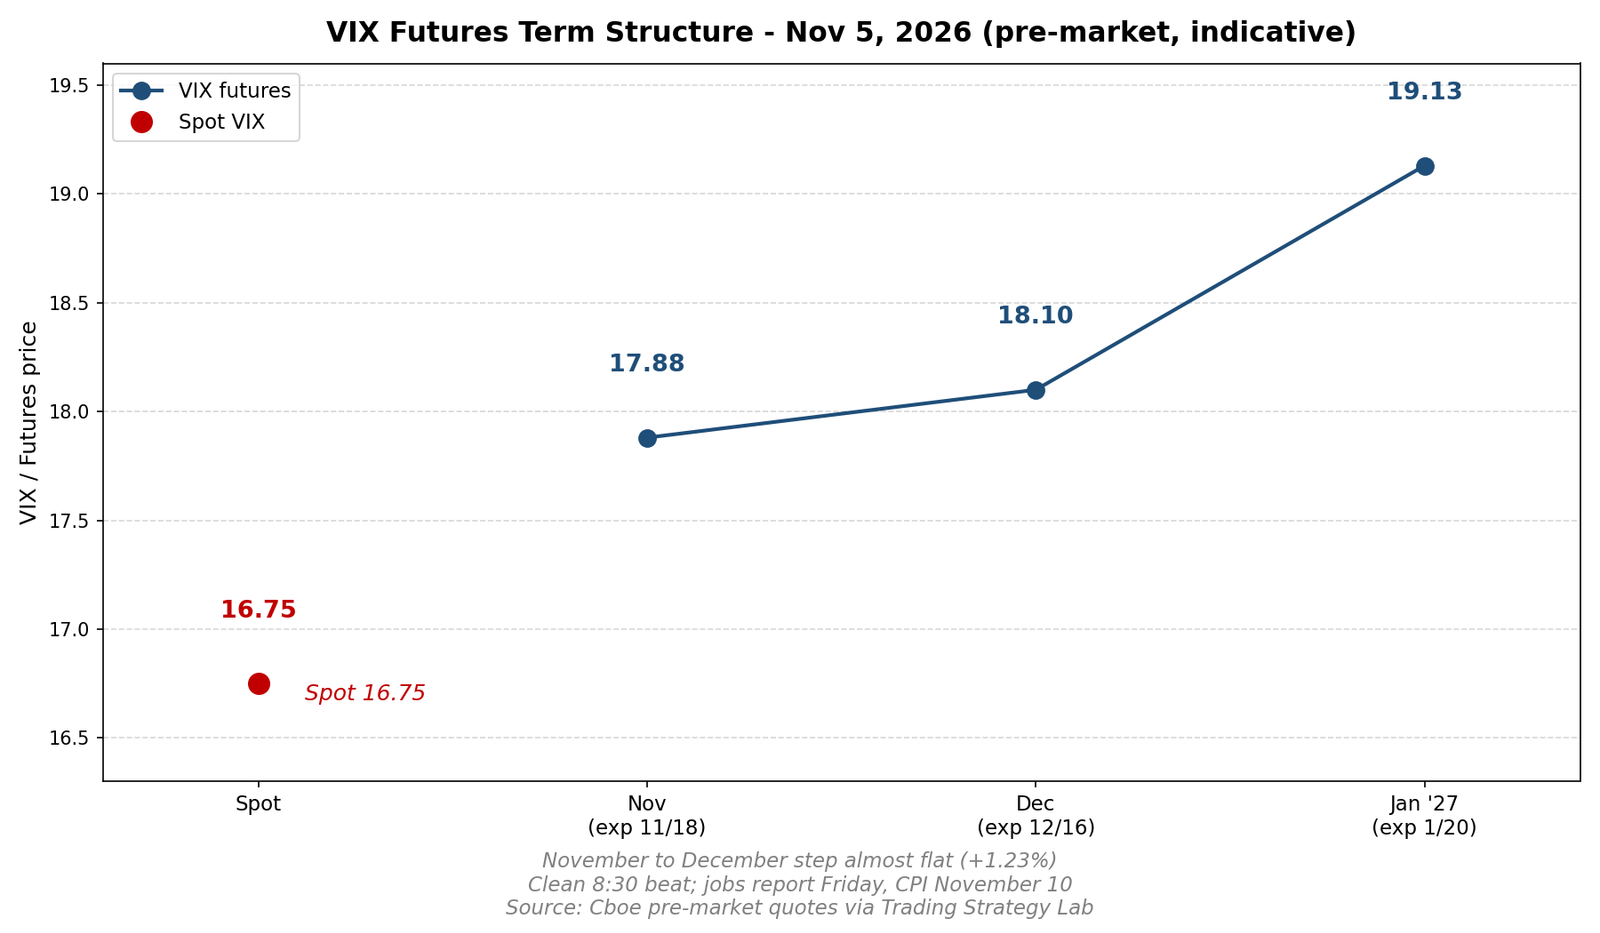
Spot volatility sits at 16.75 this morning, up 0.14 points from Wednesday’s close of 16.61, after Wednesday’s plunge of 20.26 percent on the post-midterm relief move. The November contract sits at 17.88 and the December contract at 18.10, so the November to December step is only plus 0.22 points, or plus 1.23 percent. That is almost flat, and it sits far below the long term median step of about 6.3 percent. In plain terms, traders are paying very little for the step into December, even though the relief rally held. The cushion underneath has improved a little: the November contract sits 1.13 points above spot, back above 1 point after yesterday’s thin 0.41, but it is still modest. The January contract sits at 19.13, so the total slope from spot to January is plus 2.38 points, but almost all of that slope sits in the December to January step of 1.03 points, not in the November to December step.
Positioning gives the same caution in plain terms. One snapshot from Wednesday’s close puts spot near 7,689 above a flip level near 7,658, with a call wall near 8,000 and a put wall near 7,000, a setup in which dealer hedging tends to damp moves rather than chase them. A second snapshot puts the flip near 7,645, the call wall near 7,690, and the put wall near 7,600, so the methods disagree on how far away the walls sit, but both agree spot is above the flip in calmer territory. The expected daily move for the S&P 500 is about plus or minus 1.06 percent.
The 8:30 data beat on all three fronts. Initial jobless claims came in at 189,000 against about 197,000 expected, with the prior week revised up to 195,000. Claims have now stayed below 200,000 for seven straight weeks, a low layoffs market, not a breaking one. Third quarter productivity rose 3.6 percent annualized against 2.9 percent expected, and unit labor costs fell 0.7 percent against about flat expected. Strong productivity with falling unit labor costs is the market friendly combination: growth without wage cost pressure, which argues against further near term tightening pressure from the labor side. The one softer detail was continuing claims, up 23,000 to 1,718,000, a reminder that hiring is still slow to reabsorb the unemployed.
Two other pressures are worth watching. The 10 year Treasury yield sits at about 4.904 percent this morning, up about 1 basis point and still below the 5 percent round number. Oil is higher this morning, with West Texas crude about 89.27 dollars, up about 1.31 percent, after Wednesday’s 8.3 percent collapse to 88.12 dollars on hopes of a faster end to the United States and Iran conflict. Gold is about 4,133.90 dollars this morning, up about 1.50 percent, after Wednesday’s 3.4 percent jump back above 4,000 dollars, and the dollar index is about 101.63. The Bank of England raised its base rate to 4.00 percent from 3.75 percent this morning, an 8 to 1 vote and the first hike since August 2023, and warned at least one more increase was likely if the United States and Iran conflict continues.
Market news this morning, with no position framing, is a rotation, not a retreat. Dow and S&P futures hold up while Nasdaq futures lag on a chip sell-off: Qualcomm fell about 10 percent premarket after missing fourth quarter estimates, Arm fell about 7 percent, and Asian chip stocks sold off overnight. AppLovin rose about 22 percent on a beat, while CAVA fell about 8 percent, Dutch Bros fell about 12 percent after cutting its outlook, and Expedia fell about 7 percent. After the close today: Airbnb, Cloudflare, and Monster Beverage, plus Microchip Technology.
The December question will not go away. The Fed target range was held at 3.75 to 4.00 percent on October 28 on a 10 to 2 vote, with Governor Cook and Cleveland Fed President Hammack dissenting in favor of an immediate hike. The next meeting is December 8 to 9. Market pricing as of November 4 put a December hike at about 78 percent, which still prices a hike as the base case, not as a coin flip. For a December hike to be taken off the table, inflation needs to keep cooling, and the next tests are Friday’s payrolls report and the November 10 CPI report. Fed speakers tonight include Cleveland Fed President Beth Hammack, Richmond Fed President Thomas Barkin, and Dallas Fed President Lorie Logan, all three of whom have leaned hawkish since the October meeting.
What is next: Friday brings the October employment report at 8:30 AM, with payrolls expected up about 65,000 after September’s 29,000, unemployment at 4.2 percent, and average hourly earnings up 0.3 percent month over month. That report does the repricing before anything else does.
What changes the read: the November to December step widening materially toward a healthy slope, with spot volatility settling and holding lower and real cushion rebuilding underneath it, would support a calmer read. A move back above 20 in spot volatility, or the November to December step inverting again, would push us back toward RED. Until the November to December step pays more for the risk ahead, we stay defensive and patient, with no hurry to chase this morning’s relief rally into Friday’s payrolls report.
Educational market analysis only. Not investment advice. See Terms of Use.
Leave a Reply