November 10, 2026
Our regime read is unchanged: RED, risk-off posture. Monday’s relief rally is on hold. October CPI came in hot this morning, core inflation stuck at 0.3 percent for a third straight month, and spot volatility is back above 20 less than a day after closing under it. We stay defensive into Friday’s October PPI.
The inflation print is the story today. Headline CPI rose 0.4 percent on the month against 0.3 percent expected, and core rose 0.3 percent against 0.2 percent expected. Core has now printed 0.3 percent in August, September, and October, which is the number the Fed watches most closely. There is no year over year rate this month, because the government shutdown last year meant no October 2025 prices were collected, so there is no base month to compare against. Shelter rose 0.3 percent and made up more than 30 percent of the monthly increase, food jumped 0.5 percent, and energy slowed to 0.7 percent after September’s 5.2 percent surge.
The market reaction is a rates up, stocks down tilt. S&P 500 futures sit near 7,550, down about 0.32 percent, after Monday’s close of 7,549.94, up 2.35 percent, the best day since April. Nasdaq 100 futures sit near 27,757, down about 0.92 percent, after the Nasdaq Composite closed Monday at 25,253.14, up 2.74 percent. Dow futures sit near 52,525, up about 0.05 percent, after the Dow closed Monday at 52,389.75, up 2.15 percent. The Dow is holding up while tech lags. Nvidia is still working through the board investigation into chief executive Jensen Huang, and the shares fell 4.3 percent Monday, edging higher before the open.
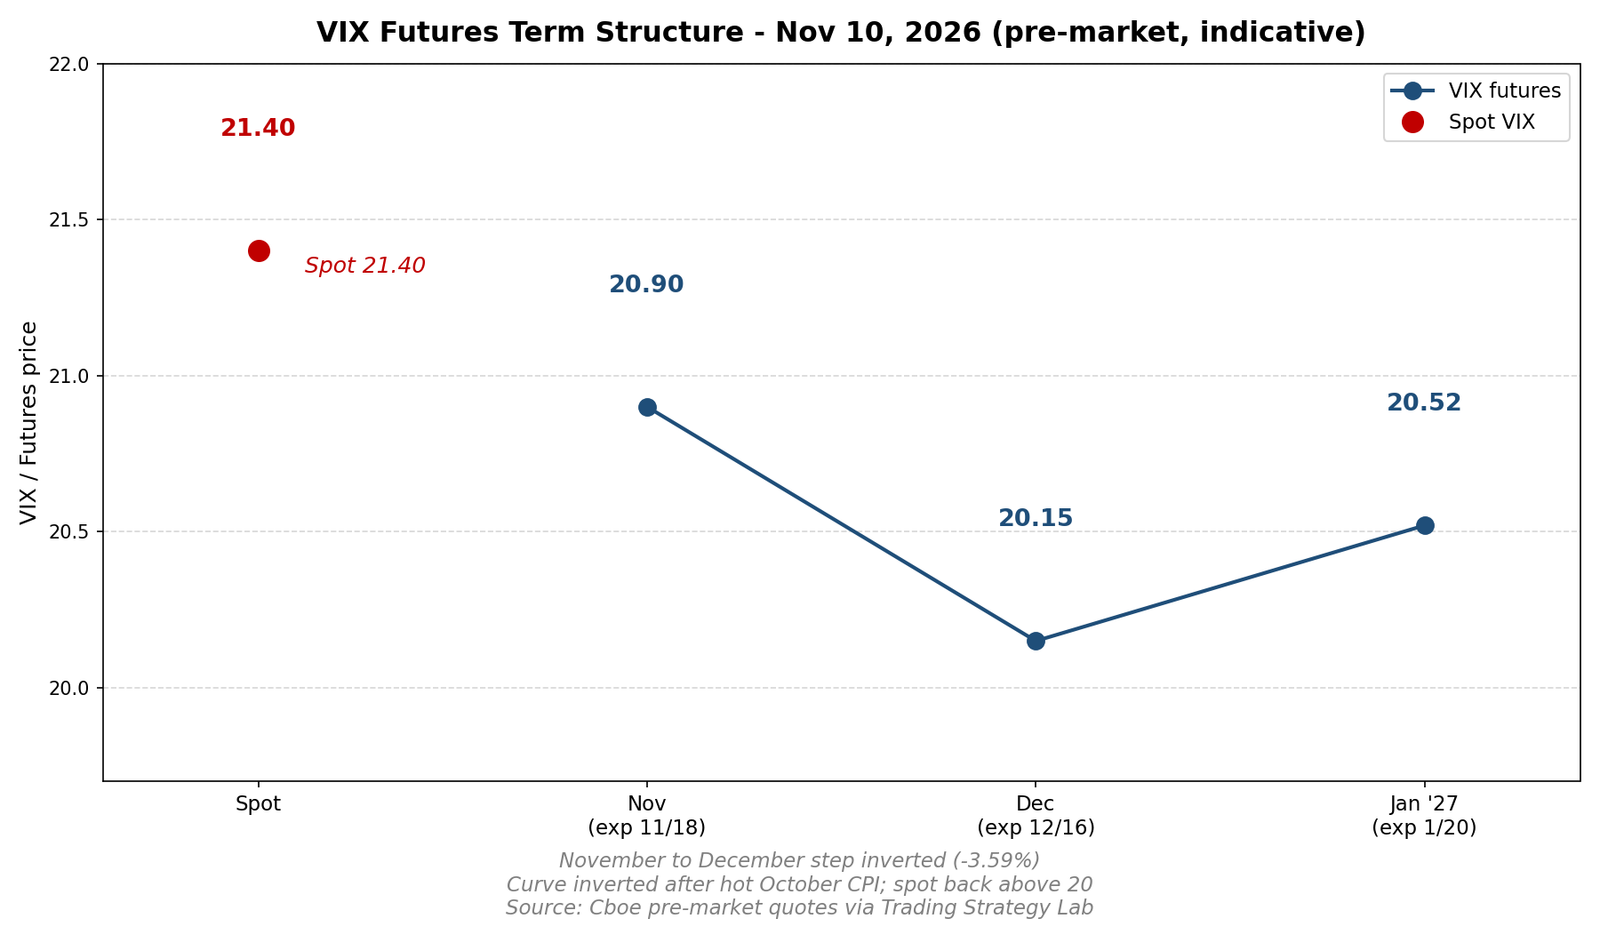
This morning spot volatility sits at 21.40, up from Monday’s close of 19.92, when it fell 22.3 percent on the day. The shape of the curve is the problem, not the level alone. The November contract sits at 20.90 and the December contract at 20.15, so the December contract sits 0.75 points below the November contract, a downward step of 3.59 percent. The January contract sits at 20.52, so the curve slopes down from spot through December, then flattens. Spot volatility sits 0.50 points above the November contract, so there is no cushion underneath at all. In plain terms, the market is paying for near term stress and pricing calmer volatility further out, and a downward sloping curve is itself the stress signal, not a buying opportunity. Monday gave back the calm in about an hour.
Positioning gives the same warning in plain terms. Dealer hedging sits in short gamma territory, which means hedging tends to amplify moves in either direction rather than damp them. One snapshot puts the flip level near 7,663, with a call wall near 7,700 and a put wall near 7,500, and Monday’s S&P 500 close of 7,549.94 sits about 113 points below the flip, in negative gamma territory. The expected daily move for the S&P 500 is about plus or minus 1.35 percent, roughly 102 points.
The December rate decision is now the open question. Governor Waller said in a London speech this morning that a 50 basis point December hike should be considered if October core ran around 0.3 percent or hotter, and it printed exactly 0.3 percent. Futures had priced about 84 percent odds of a 25 basis point December hike going into the print, with only about 3 percent on 50 basis points or more, so watch for repricing now that Waller’s threshold is met. The Fed funds target is 3.75 to 4.00 percent, and the next meeting is December 8 to 9. The 10 year Treasury yield sits near 4.91 percent, through the 4.90 percent round number, with the 2 year near 4.62 percent and the 30 year near 5.27 percent.
The rest of the week keeps the focus on inflation and rates. Wednesday is Veterans Day, with bond markets closed and stocks open. Thursday brings weekly jobless claims and a 30 year bond auction. Friday brings October PPI at 8:30 AM, which will confirm or challenge today’s CPI message. Today also brings a 42 billion dollar 10 year note auction at 1:00 PM, and Fed speakers include Dallas Fed President Logan at 9:35 AM, Kansas City Fed President Schmid at 1:30 PM, and Vice Chair for Supervision Bowman at 3:30 PM and again at 6:30 PM. West Texas crude sits near 85.80 dollars, gold near 4,120 dollars, and the dollar index near 101.7.
What changes the read: a soft PPI that brings spot volatility back under 20 and lets the November to December step turn back to a healthy upward slope would support a calmer read. Until the curve flips back, we stay RED, defensive and patient, with no hurry to buy into a tape where dealer hedging amplifies every move.
Educational market analysis only. Not investment advice. See Terms of Use.
Leave a Reply