Market Regime: AI Rebound Pulls the Read to AMBER Ahead of Friday’s PPI
November 11, 2026
Our regime read has changed: AMBER, continue defensive posture. Yesterday’s read was RED. The AI trade is bouncing back this morning after Tuesday’s inflation hit, and spot volatility is back under 20, but the curve has only just flipped out of inversion, so we are not out of the woods yet. The next real test is Friday’s October PPI.
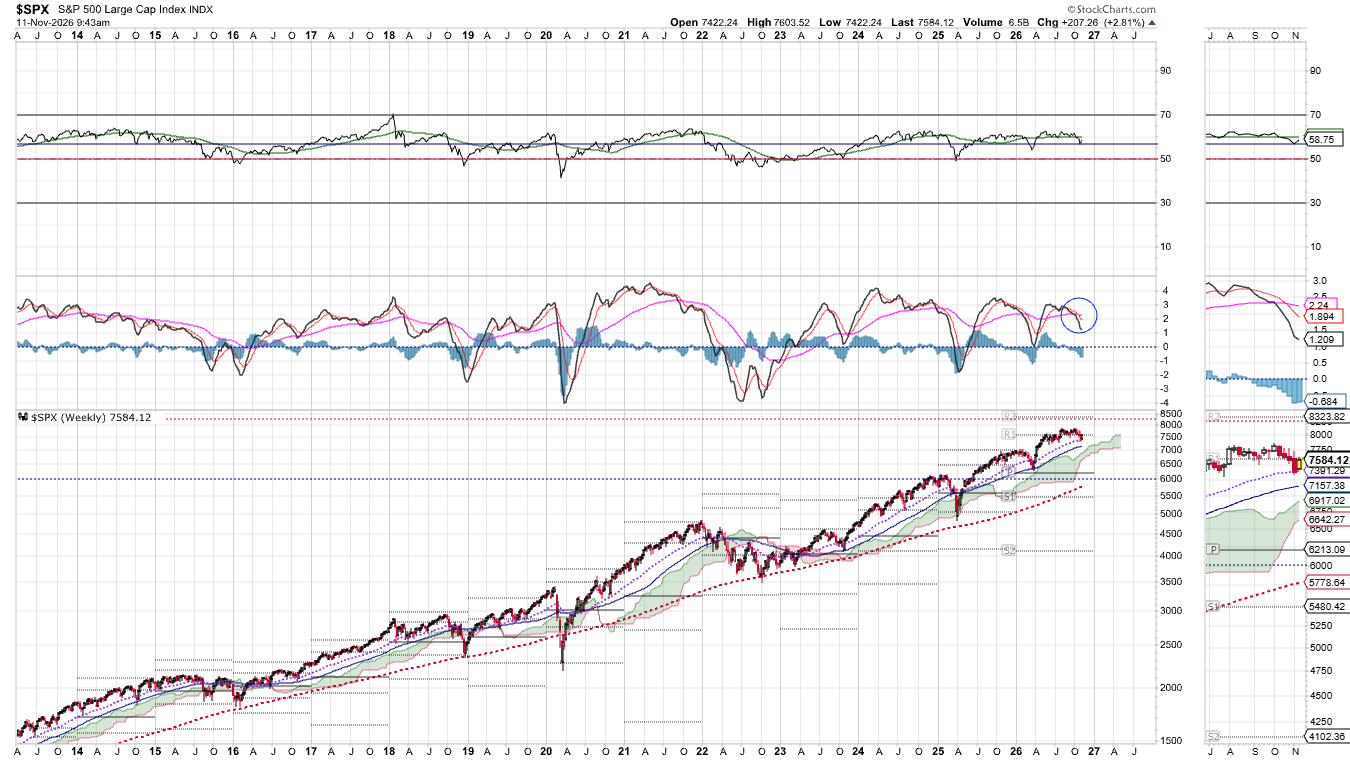
The rebound is led by tech. S&P 500 futures sit near 7,607, up about 0.83 percent, after Tuesday’s close of 7,520.93, down 0.38 percent. Nasdaq 100 futures sit near 28,355, up about 1.8 percent, after the Nasdaq Composite closed Tuesday at 25,065.88, down 0.74 percent. Dow futures sit near 52,371, up about 0.11 percent, after the Dow closed Tuesday at 52,231.89, down 0.30 percent. CoreWeave reported third quarter revenue of 3,661 million dollars and raised its 2026 outlook to 13.0 to 13.3 billion dollars, and the shares are up 11 to 15 percent before the open. Nvidia is up about 5.2 percent before the open after falling 5.5 percent Tuesday, its second straight down day. Monday’s 2.35 percent relief rally is now about half given back over two sessions.
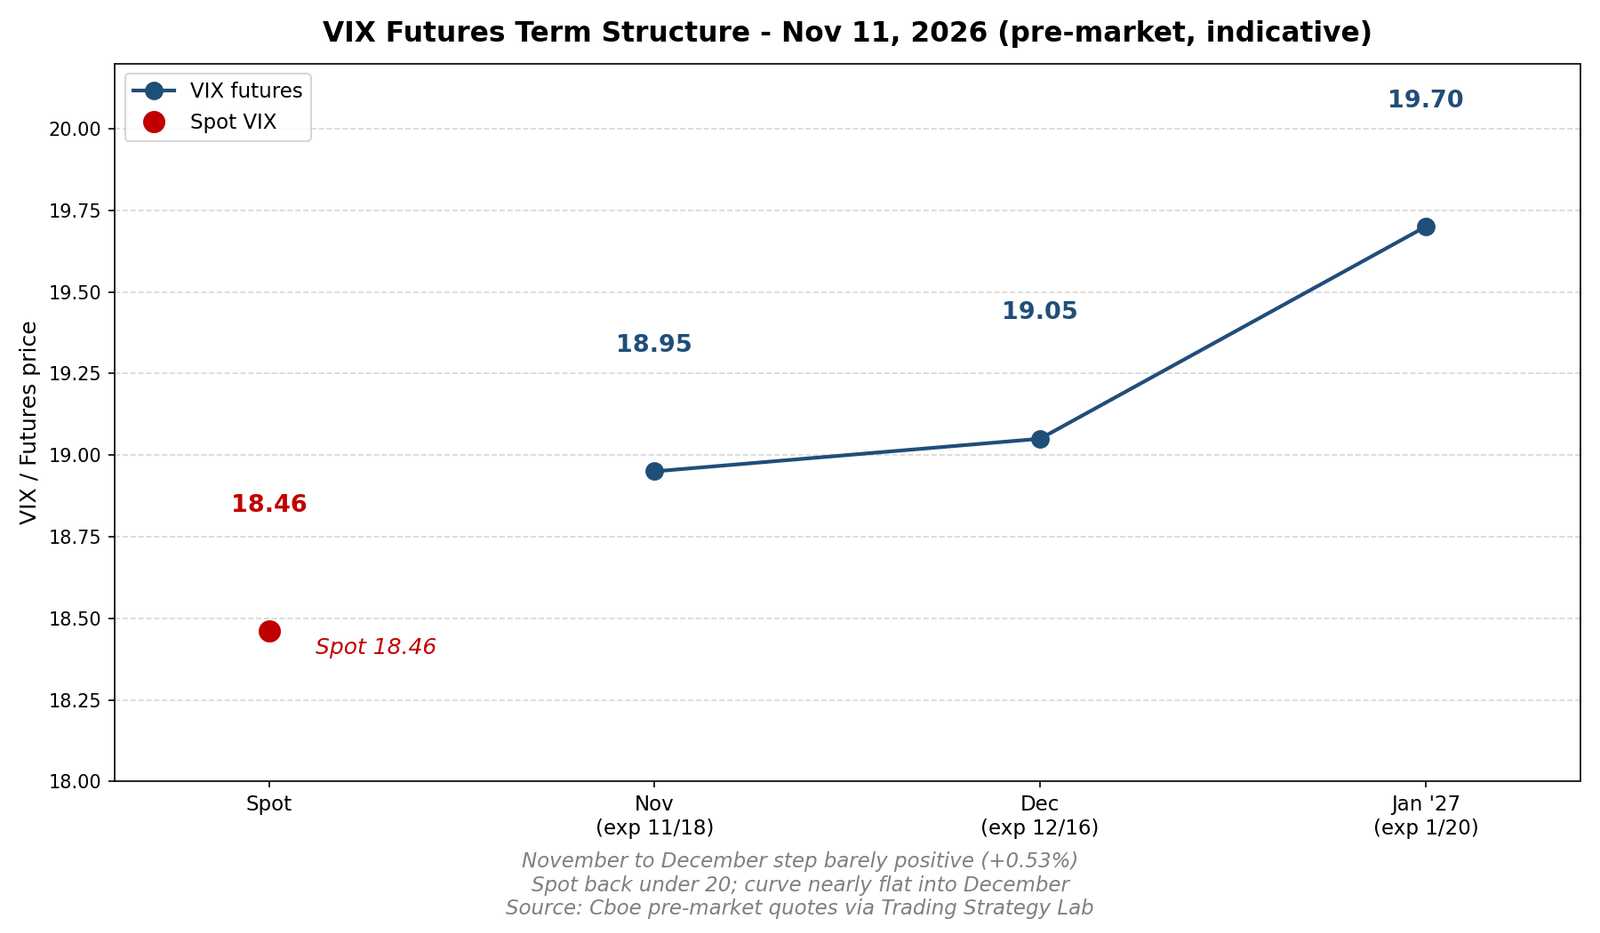
This morning spot volatility sits at 18.46, down from Tuesday’s close of 19.46 and back under the 20 line for a second straight session after Tuesday morning’s post CPI spike to 21.40. The shape of the curve is the story, not the level alone. The November contract sits at 18.95 and the December contract at 19.05, so the December contract sits just 0.10 points above the November contract, an upward step of 0.53 percent. The January contract sits at 19.70, so the curve slopes gently upward from spot through January. Spot volatility sits 0.49 points below the November contract, so there is almost no cushion underneath. In plain terms, the market is treating the CPI shock as a passing event, not a break in the regime, but it is paying almost nothing for that view. This is the first positive reading at the front of the curve after four straight inverted readings, and the curve is flattest exactly where the event risk is densest, in December, which holds the October PCE report, November payrolls, and the December 8 to 9 Fed meeting.
Positioning gives the same cautious message in plain terms. Dealer hedging sits in short gamma territory, which means hedging tends to amplify moves in either direction rather than damp them. One snapshot puts the flip level near 7,640, with a call wall near 7,700 and a put wall near 7,500, and Tuesday’s S&P 500 close of 7,520.93 sits about 119 points below the flip, in negative gamma territory, with the put wall at 7,500 touched during the session. This morning’s futures rally to near 7,607 would put the open just under the flip level, a zone where the mood can change fast. The expected daily move for the S&P 500 is about plus or minus 1.16 percent, roughly 88 points.
The rate problem has not gone away. October CPI, the print that sets the week, came in hot: headline up 0.4 percent on the month against 0.3 percent expected, and core up 0.3 percent against 0.2 percent expected, the third straight month at 0.3 percent, which is the number the Fed watches most closely. Futures now price about 91 percent odds of a 25 basis point December hike, with about 9.1 percent on 50 basis points, and a pause fully priced out. Governor Waller said a 50 basis point December hike should be considered if October core ran around 0.3 percent or hotter, and it printed exactly 0.3 percent. Dallas Fed President Logan said the Fed needs at least two more quarter point hikes, and Chicago Fed President Goolsbee called the CPI borderline disturbing. The Fed funds target is 3.75 to 4.00 percent, and the next meeting is December 8 to 9. The 10 year Treasury yield closed Tuesday near 4.99 percent, and there is no fresh yield read today because the cash bond market is closed for Veterans Day. The 5 percent round number is the line to watch when bonds reopen Thursday.
There are no US economic releases today, and no Fed speakers are scheduled on the Veterans Day calendar. The rest of the week keeps the focus on inflation and rates. Thursday brings weekly jobless claims at 8:30 AM, plus Applied Materials and Cisco earnings after the close. Friday brings October PPI at 8:30 AM, which will confirm or challenge the CPI message. A hot PPI would firm the 50 basis point chatter and push the 10 year through 5 percent when bonds reopen. A soft PPI would give the AMBER read room to steepen toward a calmer read. West Texas crude sits near 86.60 dollars, gold near 4,030 to 4,050 dollars, and the dollar index near 102.20 to 102.50.
What changes the read: a soft PPI that brings the November to December step back to a healthy upward slope and keeps spot volatility under 20 would support a calmer read. Until the curve steepens, not just flips positive, we stay AMBER, defensive and patient, with no hurry to buy into a tape where dealer hedging amplifies every move.
Educational market analysis only. Not investment advice. See Terms of Use.
Leave a Reply