November 14, 2026
Inflation re-accelerated this week, and the December hike is now locked in at 100%. October CPI came in hot on Tuesday, October PPI came in a touch cooler on Friday, and neither print changed the main event, only the argument about the size of the hike. Stocks rallied anyway, their best week since August, while bonds had their worst week since April 2025.
This week’s scorecard:
| Release | Date | Actual | Consensus | Prior | Verdict |
|---|---|---|---|---|---|
| Headline CPI m/m (Oct) | Nov 10 | +0.4% | +0.3% | +0.6% | NEGATIVE |
| Core CPI m/m (Oct) | Nov 10 | +0.3% | +0.2% | +0.3% | NEGATIVE |
| NFIB Small Business Optimism (Oct) | Nov 10 | 97.8 | 98.1 | 97.9 | NEGATIVE |
| Initial Jobless Claims (wk ended Nov 7) | Nov 12 | 200K | 195K | 191K (rev.) | NEGATIVE |
| Continuing Jobless Claims (wk ended Oct 31) | Nov 12 | 1.697M | n/a | 1.717M | POSITIVE |
| Existing Home Sales, SAAR (Oct) | Nov 12 | 3.75M | 3.85M | 3.99M | NEGATIVE |
| Headline PPI m/m (Oct) | Nov 13 | +0.3% | +0.4% | +1.4% (rev.) | POSITIVE |
| Headline PPI y/y (Oct) | Nov 13 | +6.5% | +6.6% | +6.3% | POSITIVE |
| Core PPI m/m (Oct) | Nov 13 | +0.3% | +0.3% | +0.8% (rev.) | IN-LINE |
| Core PPI y/y (Oct) | Nov 13 | +5.0% | +5.0% | +5.0% | IN-LINE |
| PPI ex food, energy, trade m/m (Oct) | Nov 13 | +0.5% | ~+0.4% | +0.5% | NEGATIVE |
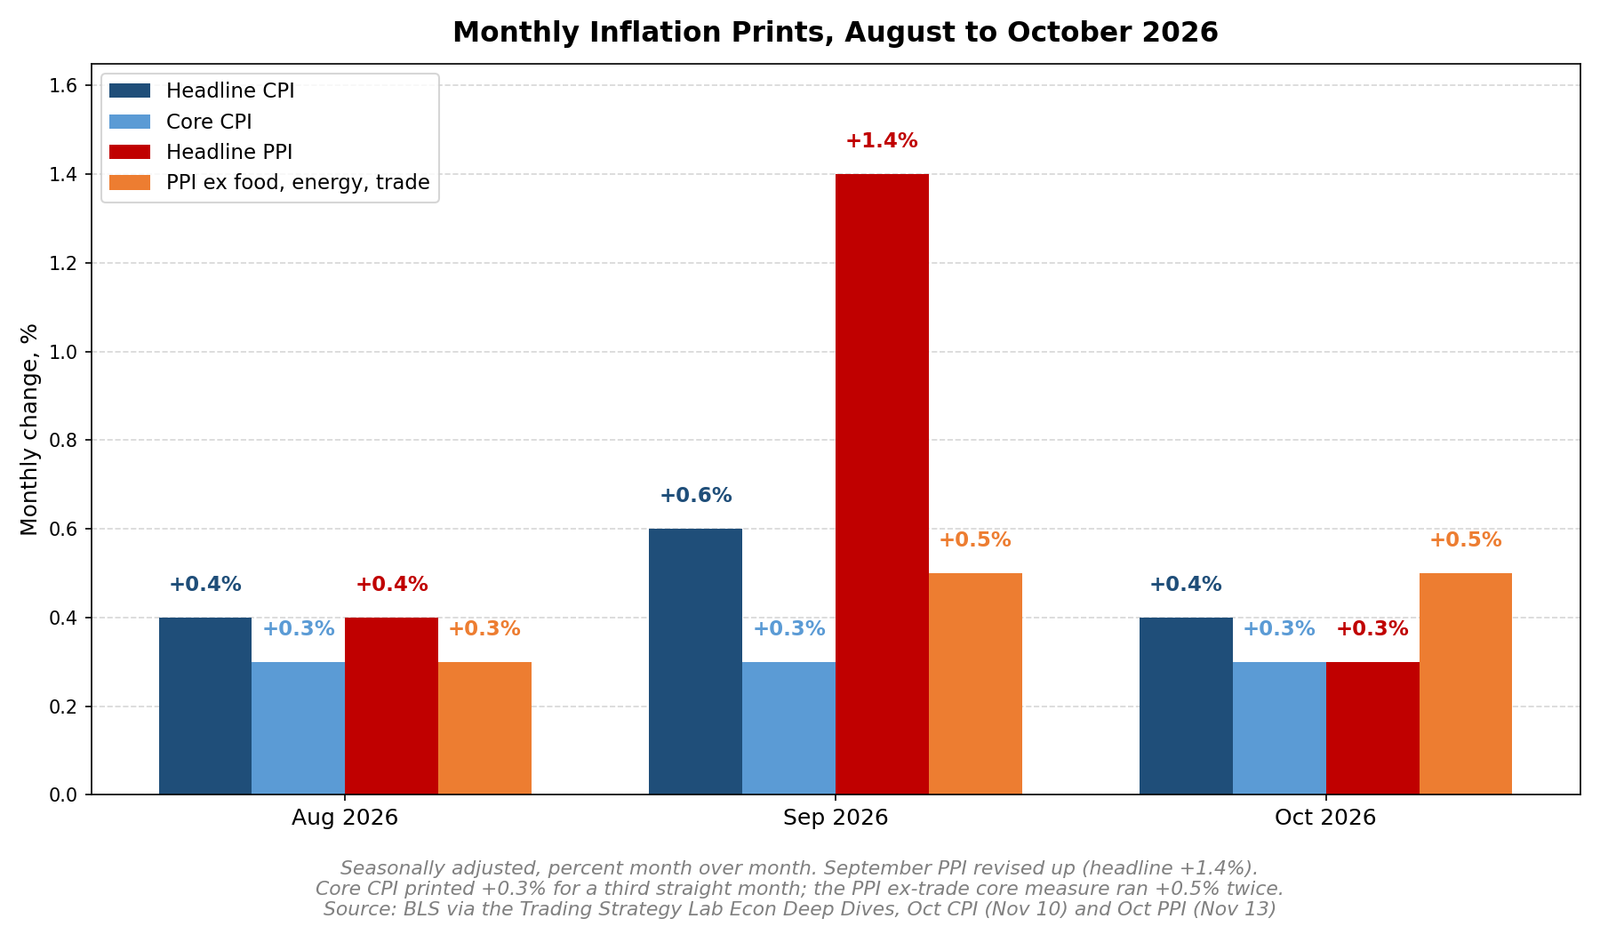
October CPI: hot on both lines, core stuck at +0.3%.
- Headline +0.4% vs +0.3% expected; core +0.3% vs +0.2% expected. Third straight month of core at +0.3%.
- Food did the damage, +0.5% after flat September. Services stayed sticky across the board; used cars, -1.2%, was the one clear disinflationary item.
- No official year-over-year rate this month: the BLS collected no October 2025 prices during last year’s shutdown. Last official annual readings are September’s, headline +3.7%, core +2.6%.
- Fed Governor Waller’s trigger was core at +0.3% or more, and core printed exactly +0.3%. After the print, CME FedWatch put a December hike at 100%, with 89% for 25bp and 11% for 50bp.
The monthly run rate is the whole story, and it points the wrong way: the three-month annualized pace is about 5.7% on headline and about 3.7% on core, up from roughly 0.8% and 1.6% over the May-to-July window. Core has stopped improving.
October PPI: a touch cooler, with energy doing the cooling.
- Headline +0.3% vs +0.4% expected, +6.5% year over year vs +6.6%. Core exactly on consensus at +0.3% (+5.0% year over year).
- Energy flipped to -0.1% after September’s +10.0% surge; diesel down 7.9%. Services cooled to +0.2% after September’s revised +1.0%.
- The details stayed hot: final demand goods +0.5%, up +10.2% over the year, the largest 12-month rise since October 2022. Food +1.3%. Transportation and warehousing +2.0% on the month, +18.5% over the year.
The direction matches Tuesday’s read, re-acceleration, not cooling, but the monthly step was smaller than September’s. The three-month annualized pace is about 8.7% on headline PPI and about 5.3% on the ex-trade core measure. September was revised hotter, and October’s figures are preliminary.
The Fed path.
- The December hike is locked in at 100%, with 25bp the base case and 50bp a live minority at about 11%. Friday trimmed the 50bp case by about 3 points; one week ago the market still gave a hold a 23.7% chance, and that is now gone.
- The Fed held at 3.75% to 4.00% on October 28 in a 10-2 vote. Bank of America and Deutsche Bank now call for 25bp hikes in December, January, and March, a terminal rate of 4.50% to 4.75%.
| December and January hike odds (CME FedWatch) | 25bp | 50bp | 75bp |
|---|---|---|---|
| December 8-9 meeting | ~89-91% | ~9-11% | n/a |
| Cumulative hikes by January 27, 2027 | ~24% | ~65% | ~11% |
The two prints disagree on the month and agree on the trend. The debate has moved from whether December happens to how many more hikes follow, and a hold would now need a major downside surprise from the November jobs report on December 4.
Labor and housing.
- Initial claims ticked up to 200K, a small miss against 195K expected, but claims have sat at or below 200K since mid-September. Continuing claims fell to 1.697M.
- Existing home sales fell to a 3.75M annual rate, down 5.5% on the month and the lowest since August 2010. Small business optimism slipped a third straight month to 97.8.
No layoff wave for the Fed to lean on, and housing is where higher rates are already showing up.
Markets: best week since August.
- S&P 500 closed Friday at 7,561.67, down 0.40% on the day but up 2.51% on the week. Nasdaq 25,136.27, down 0.91% Friday, up 2.27% on the week. Dow 52,347.55, up 0.10% Friday, up 2.07% on the week.
- All 11 sectors rose. Energy led at +5.4%, followed by Industrials +3.8%, Communication Services +3.7%, and Technology +3.4%. Breadth was better than the headline: more than 60% of S&P 500 stocks rose on Friday even as the index fell.
- The biggest moves were single-name led: Nvidia’s board confirmed CEO Jensen Huang’s resignation Thursday, and AMD dropped 8.75% Friday after a five-session 44.7% run.
Signal: MIXED. Stocks gained 2.5% with all 11 sectors higher, but the rally was a rebound from oversold levels, not a vote of confidence. The macro data argues for caution; the tape argues the selling is exhausted for now.
Bonds: worst week since April 2025.
- The 10-year closed Friday at 5.15%, up about 29bp on the week, and the 2-year closed at 4.88%, up about 35bp, its biggest weekly jump since September 2024. The 30-year closed at 5.47%.
- The curve flattened as the front end did the moving: the 2s10s slope is about +27bp, down from about +35bp a week ago.
- No growth-scare bid: high-yield spreads tightened to about 320bp (ICE BofA, Nov 12) from 330bp, while gold fell about 4.6% and bitcoin dropped through its 200-week average to near $68,400.
Signal: HIGHER-FOR-LONGER. The bond market spent the week repricing the Fed path higher, not pricing a slowdown. Until an inflation print comes in genuinely soft, yields have no reason to retrace.
Volatility curve.
- Friday closes: spot VIX 19.30, November futures 19.11, December 19.44, January 20.19.
- The November to December spread is +0.33 points, +1.73%, far below the roughly 6.3% long-term median. The curve flipped from inverted a week ago to upward sloping, with the front contract falling 4.58 points on the week.
Thin slope: the market sees the December hike as a near-certainty, not a two-sided risk.
Nowcasts.
- Atlanta Fed GDPNow for Q4 2026 is 3.5% (November 9 update, up from 3.4% on November 4). Cleveland Fed’s inflation nowcast puts October headline CPI around 3.7% year over year and core PCE around 3.2%; for Q4 as a whole, on an annualized quarterly pace, about 5.3% for CPI and 3.3% for core PCE.
Bottom line: inflation is holding hot while growth stays firm, which is why the Fed has room to keep hiking.
Next week preview (all ET):
| Day | Time | Release | Consensus | Prior |
|---|---|---|---|---|
| Tue Nov 17 | 8:30 AM | Retail Sales m/m (Oct) | 0.0% | +0.8% |
| Tue Nov 17 | 8:30 AM | Retail Sales ex autos m/m (Oct) | +0.4% | +0.9% |
| Wed Nov 18 | 8:30 AM | Housing Starts (Oct) | 1.23M | 1.221M |
| Wed Nov 18 | 2:00 PM | FOMC Minutes (Oct 28 meeting) | n/a | n/a |
| Thu Nov 19 | 8:30 AM | Initial Jobless Claims (wk ended Nov 14) | n/a | 200K |
| Fri Nov 20 | 10:00 AM | Michigan Consumer Sentiment final (Nov) | 51.0 | 48.0 |
Three that matter:
- Tuesday’s October retail sales. Hot (+0.6% or above): the consumer keeps spending through hot inflation and 7% mortgage rates, which firms the 50bp talk. Cold (flat or negative): the first real crack in the consumer after three hot inflation prints; it would revive the growth-scare side and trim hike odds.
- Wednesday’s October housing starts. Hot (above about 1.30M): builders are pushing through 7%-plus rates, so the freeze is a resale problem, not a construction problem. Cold (below about 1.15M): the freeze deepens.
- Wednesday’s FOMC minutes, 2:00 PM. Hot (broad support for more hikes): locks in December at 25bp and lifts January odds. Cold (members uneasy about hiking into a re-accelerating CPI): opens the door to a one-and-done December.
What changes the read: Tuesday’s October retail sales. A soft print (flat or negative) would revive the growth-scare side and trim hike odds; a hot one (above +0.6%) firms the 50bp talk. After that, October PCE on Wednesday, November 25.
Educational purposes only. Not investment advice. See Terms of Use.
Leave a Reply