Market Regime: Nvidia Shock Tests the AMBER Read Ahead of Friday’s PPI
November 12, 2026
Our regime read is unchanged: AMBER, continue defensive posture. The AI rebound is intact, but the AI trade itself has a leadership shock this morning, and the rate problem has not gone away. The next real test is Friday’s October PPI.
Nvidia is the overnight story, and it is dragging tech lower. The board met late Wednesday to discuss whether to remove CEO Jensen Huang, after the New York Times reported a second relationship with an Nvidia executive, following the November 8 disclosure of an investigation. The Wall Street Journal reported the board is preparing to remove him, and CNBC confirmed the meeting, but no decision had been announced as of this morning. Nvidia sits near 160 dollars before the open, down about 7.9 percent from Wednesday’s close of 173.73 dollars. William Blair downgraded the shares to Market Perform, and Citi and Stifel cut their price targets to 225 and 205 dollars. Nvidia reports third quarter results Tuesday, November 17, after the close. AMD and Broadcom are bucking the trend, up over 2 percent before the open.
S&P 500 futures sit near 7,607, down about 0.42 percent, after Wednesday’s close of 7,619.38, up 1.31 percent. Nasdaq 100 futures sit near 28,209, down about 0.92 percent, after the Nasdaq Composite closed Wednesday at 25,466.19, up 1.60 percent. Dow futures sit near 52,596, about flat, after the Dow closed Wednesday at 52,486.49, up 0.49 percent. Wednesday’s rally was led by CoreWeave, which raised its 2026 outlook, and this morning’s Nvidia news is giving back part of that calm, concentrated in tech while the Dow holds flat.
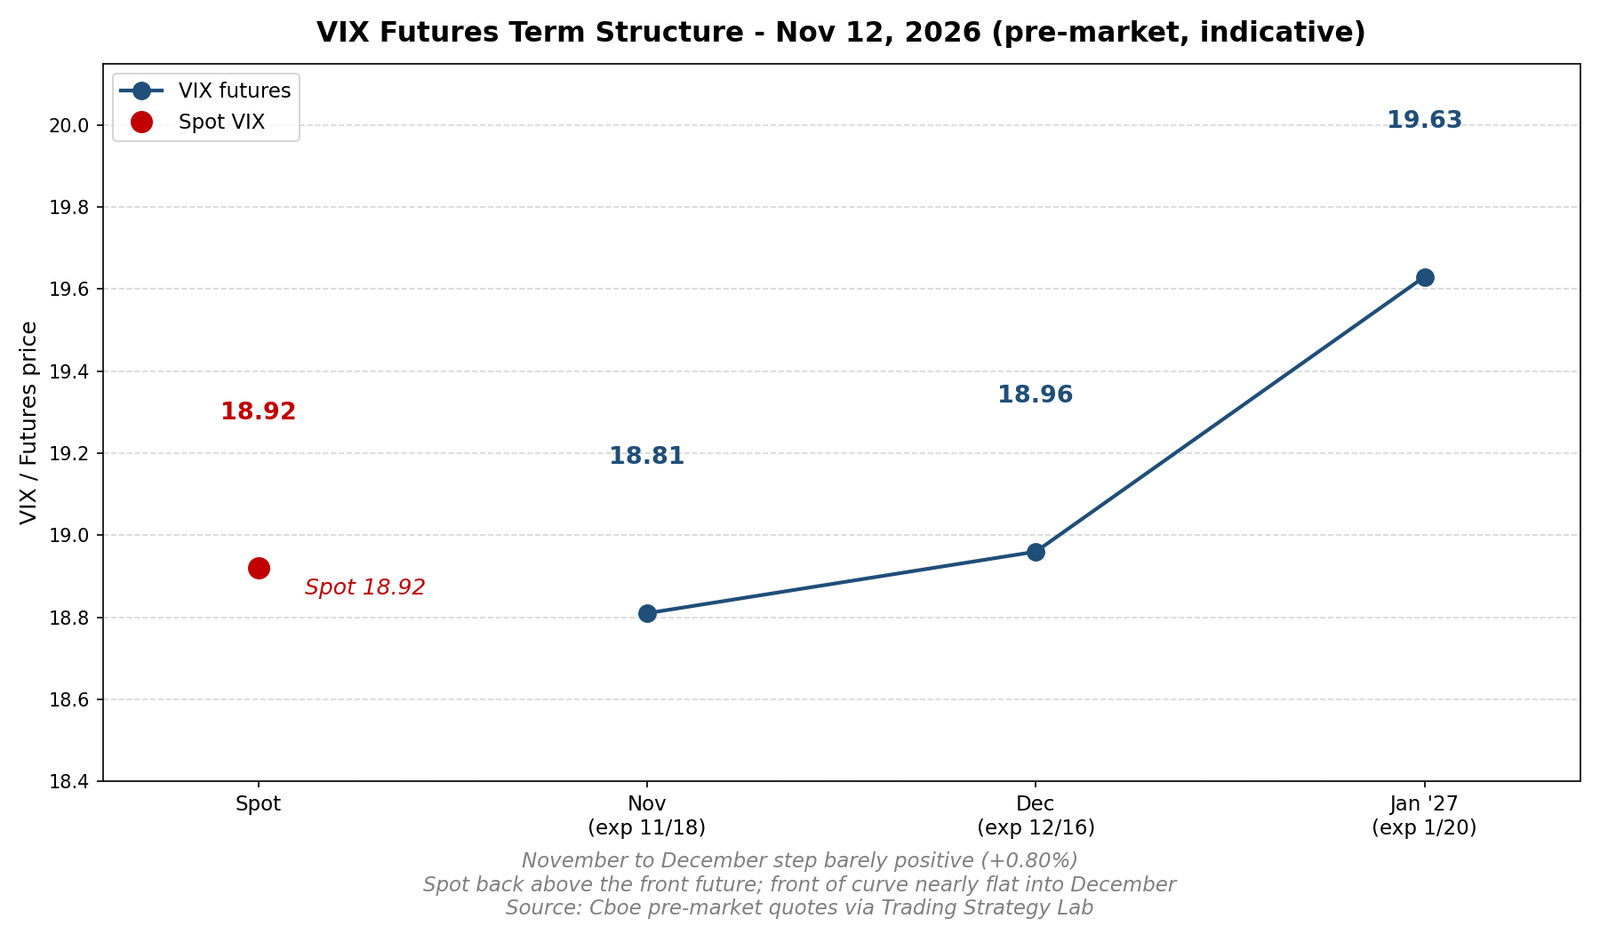
This morning spot volatility sits at 18.92, up 8.2 percent from Wednesday’s close of 17.49, and back above the November contract. The shape of the curve is the story, not the level alone. The November contract sits at 18.81 and the December contract at 18.96, so the December contract sits just 0.15 points above the November contract, an upward step of 0.80 percent. The January contract sits at 19.63, so the curve slopes gently upward from spot through January, but the front is flat to slightly inverted. Spot volatility sits 0.11 points above the November contract, so there is no cushion underneath at all. In plain terms, the market is treating the shocks as passing events, not a break in the regime, but it is paying almost nothing for that view. This is a whiplash week for the curve: it inverted hard on Friday, November 6, Tuesday morning’s hot CPI pushed spot to 21.40, and Wednesday’s bounce brought spot back under 20 with the front barely positive, only for this morning’s Nvidia shock to push spot back above the November contract. The curve is flattest exactly where the event risk is densest, in November and December, which hold Nvidia’s earnings on November 17, the Fed minutes on November 18, the October PCE report on November 25, November payrolls on December 4, and the December 8 to 9 Fed meeting.
Positioning gives the same cautious message in plain terms. Dealer hedging sits near zero, which means hedging is not positioned to dampen a move today, so it will add to whichever direction the Nvidia headline takes the tape. One snapshot puts the flip level near 7,622, with a call wall near 7,700 and a put wall near 7,500, and Wednesday’s S&P 500 close of 7,619.38 sits essentially pinned on the flip. Another read puts the flip lower, near 7,580. The providers disagree on the direction of dealer hedging at spot, so treat the 7,580 to 7,622 zone as a coin toss: a break either way can accelerate the move, and this morning’s futures open near 7,607 sits right in that zone. The expected daily move for the S&P 500 is about plus or minus 1.19 percent, roughly 90 points.
The rate problem has not gone away. The 10 year Treasury yield sits near 4.998 to 5.02 percent this morning after the bond market reopened from Veterans Day, and the 5 percent round number is the line: a hot PPI tomorrow would likely push it through. Futures price about 91 percent odds of a 25 basis point December hike, with about 9 percent on 50 basis points. Goldman Sachs now forecasts another quarter point hike in early 2027, after previously expecting the cycle to end in December. The Fed funds target is 3.75 to 4.00 percent, and the next meeting is December 8 to 9. Fed speakers today include Cleveland Fed President Hammack at 9:00 AM, Governor Barr at 10:00 AM, San Francisco Fed President Daly at 1:10 PM, and New York Fed President Williams on a panel later today. Listen for any pushback on the 50 basis point trial balloon after Tuesday’s hot CPI.
What changes the read: Friday’s October PPI, expected up 0.4 percent on the month, will confirm or challenge Tuesday’s hot CPI message. A hot PPI would firm the 50 basis point chatter and push the 10 year through 5 percent. A soft PPI would ease hike odds and give the AMBER read room to steepen toward a calmer read. Until the curve steepens, not just flips positive, we stay AMBER, defensive and patient, with no hurry to buy into a tape where dealer hedging amplifies every move and one headline can put spot volatility back above 20.
Educational market analysis only. Not investment advice. See Terms of Use.
Leave a Reply