November 13, 2026
Our regime read is unchanged: AMBER, continue defensive posture. October PPI came in a touch cooler than expected, which took a little edge off the hot inflation story, but the year-over-year rate is still the hottest since 2022, the December hike is still fully priced, and the 10-year Treasury yield is holding above 5 percent. Nothing in this morning’s data changes the read.
Producer prices rose 0.3 percent in October against 0.4 percent expected, and 6.5 percent over the past year against 6.6 percent expected. Core producer prices, which strip out food and energy, rose 0.3 percent on the month and 5.0 percent over the year, both in line with expectations. September was also revised up sharply, to 1.4 percent on the month, so the three-month trend is still hot even if this month’s print was a small step in the right direction. Futures are holding a modest gain on the news, with the S&P 500 near 7,631, up about 0.21 percent, after Thursday’s close of 7,592.40, down 0.35 percent. The Nasdaq 100 is essentially flat near 28,393, and the Dow is near 52,452, up about 0.12 percent. The Russell 2000 fell 1.66 percent Thursday to 2,799.06.
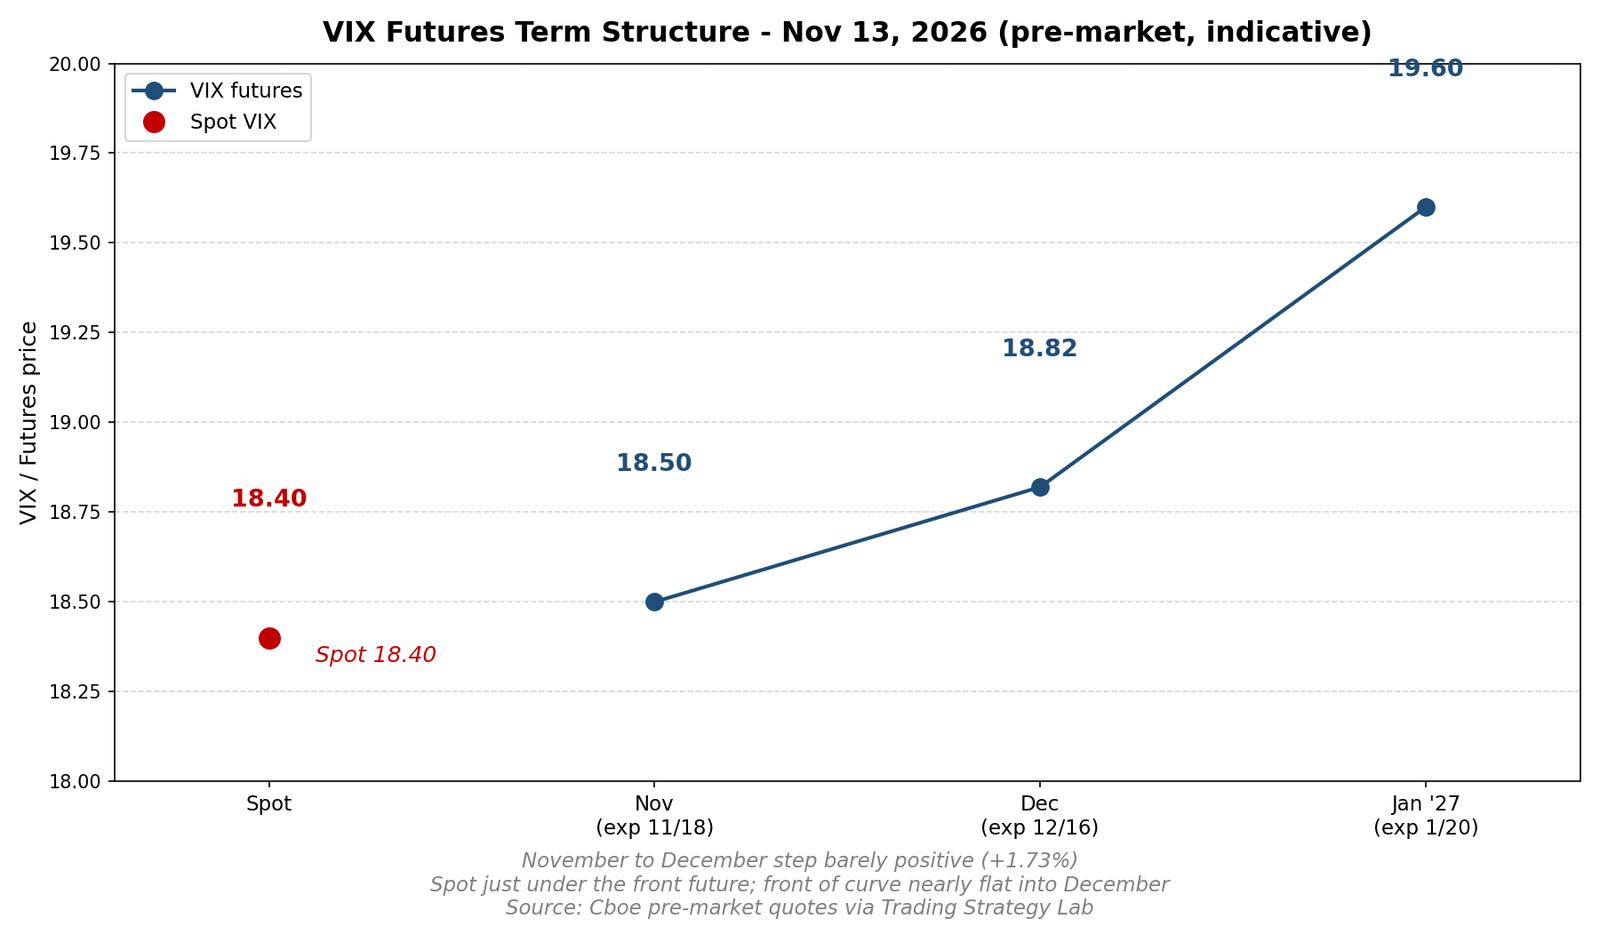
Volatility eased a little after the report. Spot volatility sits at 18.40, down about 1.6 percent from Thursday’s close of 18.70. The November contract sits at 18.50 and the December contract at 18.82, so the December contract sits just 0.32 points above the November contract, a step of 1.73 percent. The January contract sits at 19.60. The curve slopes gently upward from spot through January, but the front is nearly flat. Spot volatility sits just 0.10 points below the November contract, so there is almost no cushion underneath. In plain terms, the market is treating the inflation prints as a known problem rather than a new shock, but it is paying almost nothing for that view. The curve has now failed to steepen on nearly every reading since late October, and the December contract sits only 0.32 above November even though it holds the October PCE report on November 25, the Fed meeting on December 8 to 9, and the November CPI report on December 10. That says the market is pricing the December hike as a near certainty rather than as an event with two-sided risk.
Nvidia is the single-name story again, up about 1.8 percent before the open after losing about 11 percent on the week through Thursday following Jensen Huang’s resignation. Nvidia reports third quarter results Tuesday, November 17, after the close, and the November contract settles the next day, which is one reason it sits almost on top of spot volatility.
Positioning gives the same cautious message in plain terms. Dealer hedging sits just below its flip level near 7,594, with a call wall near 7,700 and a put wall near 7,500, and Thursday’s S&P 500 close of 7,592.40 sits just below that flip. That means hedging is not positioned to dampen a move today, so it will add to whichever direction the tape takes. The put wall at 7,500 is the nearer magnet, about 92 points below Thursday’s close, and the call wall at 7,700 is about 108 points above. The expected daily move for the S&P 500 is about plus or minus 1.16 percent, roughly 88 points.
The rate problem is the dominant cross-asset story this week. The 10-year Treasury yield sits near 5.13 percent this morning after Thursday’s weak 30-year auction and the largest two-day rise since April 2025, and Treasuries are heading for their worst week since April 2025. Futures price a 100 percent chance of a hike at the December 8 to 9 meeting, with about 88 percent on 25 basis points and about 12 percent on 50 basis points. The Fed funds target is 3.75 to 4.00 percent. Five Fed speakers are on the tape today, including Boston Fed President Collins at 9:10 AM, Dallas Fed President Logan at 9:40 AM, Vice Chair for Supervision Bowman at 10:50 AM, San Francisco Fed President Daly at noon, and Vice Chair Jefferson at 7:00 PM. Listen for any pushback on the 50 basis point chatter after Tuesday’s hot CPI, and for whether officials treat the PPI softness as meaningful. Elsewhere, oil is higher after President Trump said the US does not need a deal with Iran, with WTI crude near 88.40 dollars and Brent near 95.70 to 95.90 dollars. Gold is near 3,900 dollars, recovering slightly after Thursday’s slide of about 2.8 percent. The dollar index sits near 103.2, close to its highest since April.
What changes the read: Tuesday’s Nvidia earnings, the October PCE report on November 25, and the December Fed meeting are the next real tests. A soft November jobs report or CPI would be what takes a December hike off the table, and neither arrives before the meeting. Until the curve steepens, not just flips positive, we stay AMBER, defensive and patient, with no hurry to buy into a tape where dealer hedging amplifies every move and one headline can put spot volatility back above 20.
Educational market analysis only. Not investment advice. See Terms of Use.
Leave a Reply