Our regime read is unchanged: AMBER, continue defensive posture. Today is Fed day, and the market is waiting for the 2:00 PM decision before it reprices anything in earnest. Spot volatility looks calm enough on its own, but the shape of the curve is still the problem. The gap between the November and December contracts narrowed again overnight, to just plus 0.32%, down from plus 0.53% yesterday. That is even flatter where it matters most, right into the decision.
Tuesday’s tape closed higher. The S&P 500 finished at 7,722.60, up 0.60%, the Nasdaq gained 1.18% to 26,477.81, the Dow was nearly flat at 52,377.57, up 0.03%, and the Russell 2000 rose 1.16% to 2,818.87. This morning futures point to a mixed to slightly firmer open, with the S&P up about 0.1 to 0.2%, the Nasdaq 100 up about 0.4%, and the Dow down about 0.2%. Chips led Tuesday, helped by record results from SK Hynix that lifted memory names, with Micron up about 4% premarket.
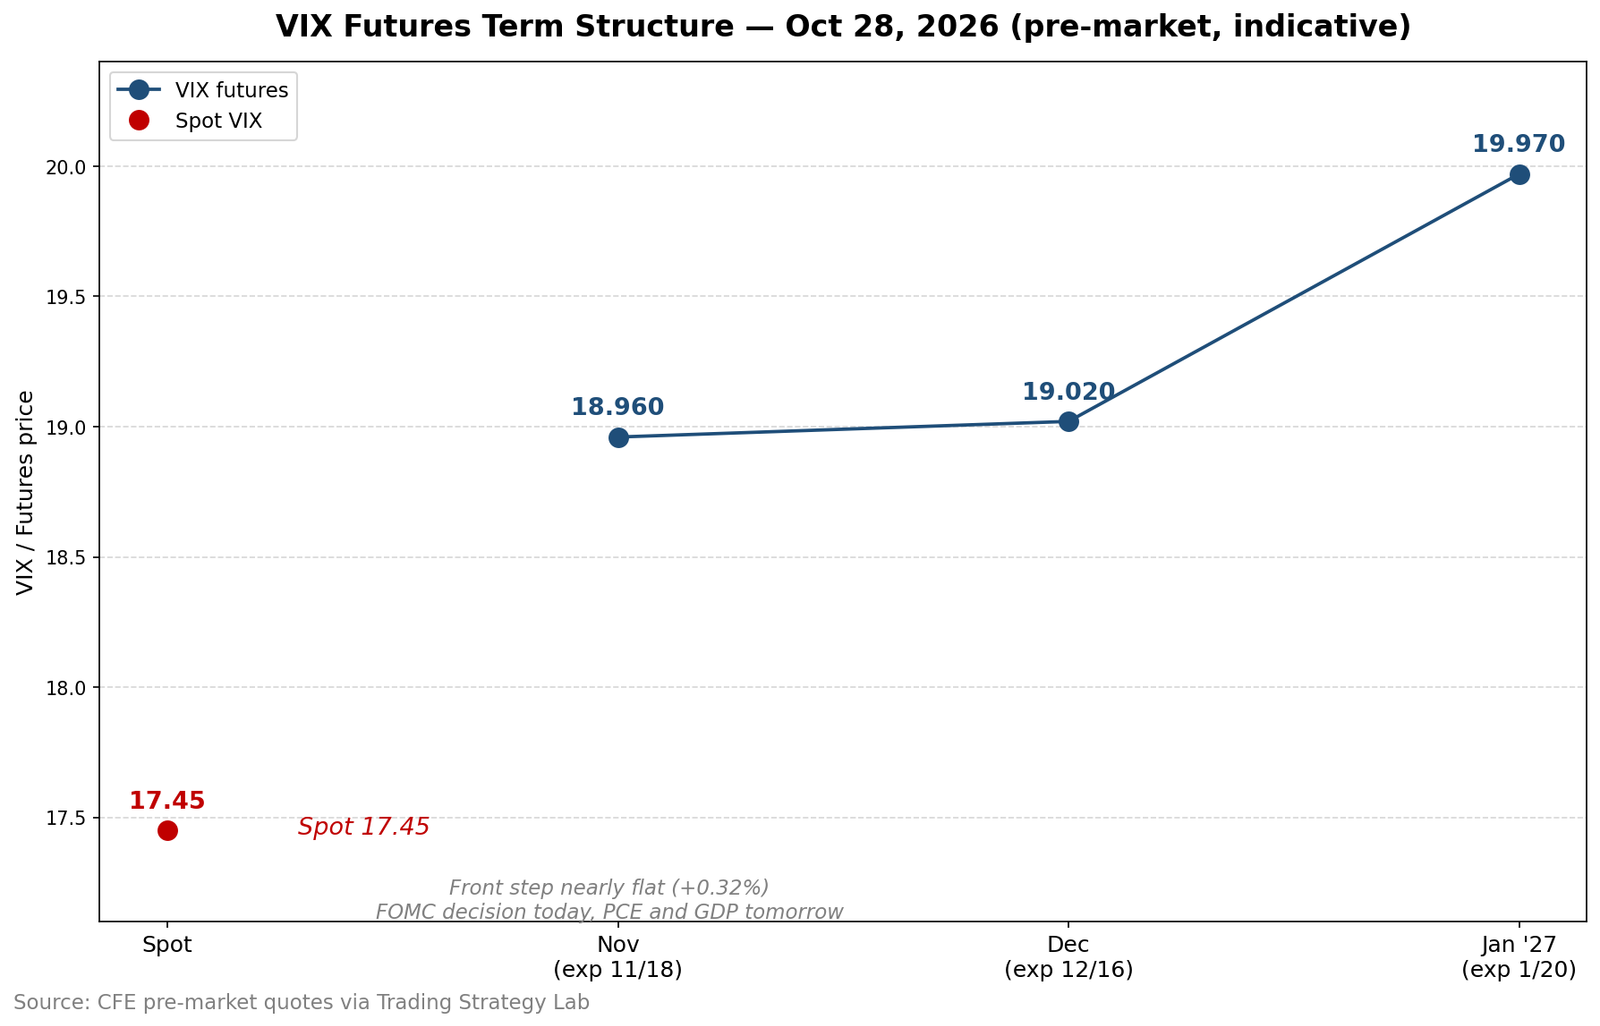
Spot VIX sits at 17.45 this morning, down slightly from Tuesday’s 17.52 close. The November contract sits at 18.96 and December at 19.02, so the market is still paying almost the same price for November volatility as for December. That is what a nearly flat pair means: traders are still paying up for the event cluster inside the November window, today’s FOMC decision, the September PCE report and Q3 GDP on Thursday morning, the November 3 midterms, November 6 payrolls, and October CPI on November 10, and discounting everything behind it. The November to December gap of plus 0.32% sits far below the long term median gap of about 6.3%, so the curve is still far from a healthy slope. There is a little cushion underneath: spot sits 1.51 points under the November contract. But the total slope across the next three months is only 2.52 points, with the November to December pair contributing just 0.06 points of it. Selling volatility right now still earns very little while event risk is at its peak, because almost no price decline is built into that first step.
Two overnight pressures are worth watching into the decision. The 10-year Treasury yield sits near 5.01 to 5.02%, above the round 5% level that has acted as a warning line all month. Oil is firmer too, with West Texas crude near $101.40 to $101.75 and Brent near $115.60, after an attack on a Saudi refinery revived supply worries. Gold is near $4,009 to $4,060, the dollar index is near 102.4, and Bitcoin is near $79,700 to $81,300.
Positioning gives a mixed read today, so we are not leaning on it hard. One snapshot puts dealers in a position where their hedging damps moves, with a flip level near 7,670, a put wall near 7,650, and a call wall near 7,680. A separate note puts dealers in the opposite position overall, with a one-day range of 7,609 to 7,745. When two methods disagree this plainly, the plain read is to treat the positioning as unsettled, not settled. The levels from this morning’s published report are clearer: the week to date high is 7,735, the 20-day average is 7,725, the 50-day average is 7,700, and the week to date low is 7,640, with a close above 7,750 as the next upside gate. The expected daily move is about plus or minus 1.10%.
Today’s decision is expected to be a hold, with the target range kept at 3.75 to 4.00%, and a hold priced around 93%. Chair Kevin Warsh speaks at 2:30 PM, and there are no new projections at this meeting. The open question is December. For a December hike to be taken off the table, inflation needs to keep cooling, and Brent above $115 makes that job harder. A hold with hawkish language on December keeps pressure on longer dated yields and on equities. A hold with a dovish tilt eases that pressure but risks a growth scare read if it sounds like the labor market is weakening faster than expected, after September payrolls printed just 29,000 jobs. After the close, Alphabet and Microsoft report, the day’s other major catalyst.
One caution from Tuesday’s rally: breadth was narrow in places. Nasdaq new lows numbered 239 against just 62 new highs, even as the Nasdaq rose 1.18%. That is a rally led by a few names, not broad buying, and it is one more reason not to chase exposure into the decision.
What changes the read: the November to December gap widening materially toward a healthy slope, or spot VIX settling and holding lower with real cushion rebuilding underneath it. Until one of those happens, we stay defensive: no new short-volatility harvesting into today and Thursday, strict stops on existing credit spreads, and no hurry into the FOMC.
Educational market analysis only. Not investment advice. See Terms of Use.
Leave a Reply