Our regime read is unchanged: AMBER, continue defensive posture. What changed overnight is the backdrop behind that read. The Fed held rates yesterday, and this morning brought a stronger growth print alongside inflation that is still not cooling. That combination keeps a December hike firmly in play, and it leaves the shape of the volatility curve almost as flat as it was going into the decision.
Wednesday’s tape closed higher for a third straight day. The S&P 500 finished at 7,743.98, up 0.28%, the Nasdaq gained 0.27% to 26,549.85, and the Dow rose 0.19% to 52,475.10. This morning the open is split by big tech earnings, not by the data alone. S&P 500 futures point down about 0.24 to 0.36%, Nasdaq 100 futures point down about 1.0 to 1.25%, and the Dow, which was firmer early, turned negative in the post data note.
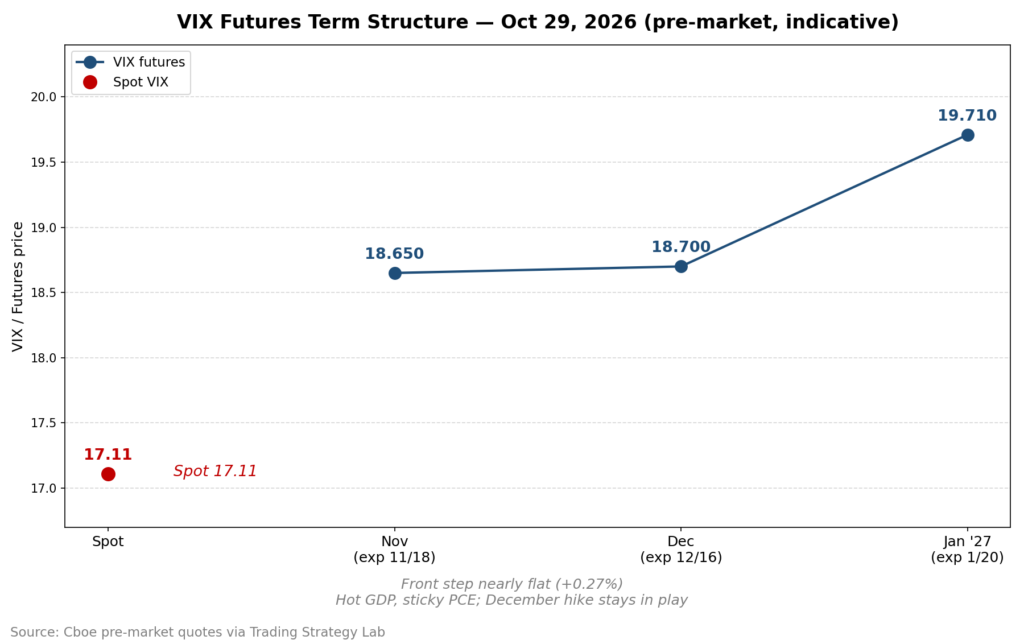
Spot VIX sits at 17.11 this morning, up slightly from Wednesday’s 16.91 close. The November contract sits at 18.65 and December at 18.70, so the market is still paying almost the same price for November volatility as for December. That gap of just 0.05 points, or plus 0.27%, is essentially unchanged from yesterday’s plus 0.32%, and it sits far below the long term median gap of about 6.3%. In plain terms, traders are still paying up for the event cluster inside the November window, today’s GDP and PCE reports, the Employment Cost Index on Friday, the November 3 midterms, November 6 payrolls, and October CPI on November 10, and discounting everything behind it. There is a little cushion underneath: spot sits 1.54 points under the November contract. But the total slope across the next three months is only 2.60 points, with the November to December pair contributing just 0.05 points of it. Selling volatility right now still earns very little while event risk is at its peak, because almost no price decline is built into that first step.
This morning’s data is why the December question will not go away. Advance third quarter GDP came in at 3.4% annualized, above consensus of about 3.1 to 3.2% and up from 2.2% in the second quarter. Headline PCE for September rose 0.5% on the month, the biggest monthly increase in six months, and 3.6% on the year, up from 3.4% in August. Core PCE rose 0.3% on the month, matching consensus, and 3.1% on the year, up from 3.0% in August. Jobless claims, at 194,000, stayed low and steady. Growth is strong enough to remove the growth scare case, while inflation is sticky enough to keep the hike case alive. For a December hike to be taken off the table, inflation needs to keep cooling, and September PCE did not cool.
The Fed backdrop fits that read. The target range was held at 3.75 to 4.00% on Wednesday on a 10 to 2 vote, with Governors Cook and Hammack dissenting in favor of an immediate hike. Chair Kevin Warsh called the next six weeks “information rich.” The next meeting is December 8 to 9. The main soft counterweight remains September payrolls, which printed just 29,000 jobs.
Earnings are doing the rest of the morning’s work. Alphabet fell about 10% after hours after missing on revenue and profit, its first double miss in nearly four years, with negative free cash flow of $9.07 billion and a 2026 capital spending plan of $195 billion to $205 billion, rising further in 2027. Microsoft rose after beating, with Azure revenue up 48% to $33.2 billion, above the $32.3 billion forecast. Amazon reports after the close today, and it is the next big test for the tech trade.
Two other pressures are worth watching. The 10 year Treasury yield sits near 5.02 to 5.04%, holding above the round 5% level that has acted as a warning line all month, with the 2 year near 4.69 to 4.70%. Oil is softer, with West Texas crude near $101.30 to $101.90, gold is near $4,028 to $4,040, the dollar index is near 102.15 to 102.26, and Bitcoin is near $80,100 to $80,200.
Positioning gives a mixed read today, so we are not leaning on it hard. One snapshot puts dealers in a position where their hedging damps moves, with a put wall near 7,700 as support, a call wall near 7,750 as resistance, and a flip level near 7,720. A separate note puts dealers in the opposite position overall, with a flip level near 7,736. When two methods disagree this plainly, the plain read is to treat the positioning as unsettled, not settled. The expected daily move is about plus or minus 1.08%.
What is next: the European Central Bank decision at 9:15 AM, with President Lagarde speaking at 9:45 AM, Friday’s Employment Cost Index and Chicago PMI, and tonight’s Amazon print.
What changes the read: the November to December gap widening materially toward a healthy slope, or spot VIX settling and holding lower with real cushion rebuilding underneath it. Until one of those happens, we stay defensive: no new short volatility harvesting into Friday’s wage data and tonight’s Amazon print, strict stops on existing credit spreads, and no hurry into the December meeting.
Educational market analysis only. Not investment advice. See Terms of Use.
Leave a Reply