The tape turned risk-off overnight and the fear gauge answered with a jump, but the curve underneath it is nearly flat. Our regime read stays AMBER, continue defensive posture.
Wednesday’s session was constructive, the S&P 500 closed up 0.36% at 7,740.42, the Nasdaq gained 1.1% to 26,703 and the Dow added 0.7% to 52,856. Premarket Thursday is a different story. S&P futures are down about 1.1%, Nasdaq futures about 1.9% and Dow futures about 0.7% as AI spending doubts came back. Tesla cut its 2026 capex forecast after beating earnings and is down 5.3% premarket, Meta is issuing new non-voting shares to fund AI spend and is down 1.9%, and Lam Research gave a disappointing outlook and is down 7%. Overnight Asia was ugly: China’s CSI 300 has fallen 20% from its June peak, a bear market, with the Nikkei, Kospi and Hang Seng each down 3% or more.
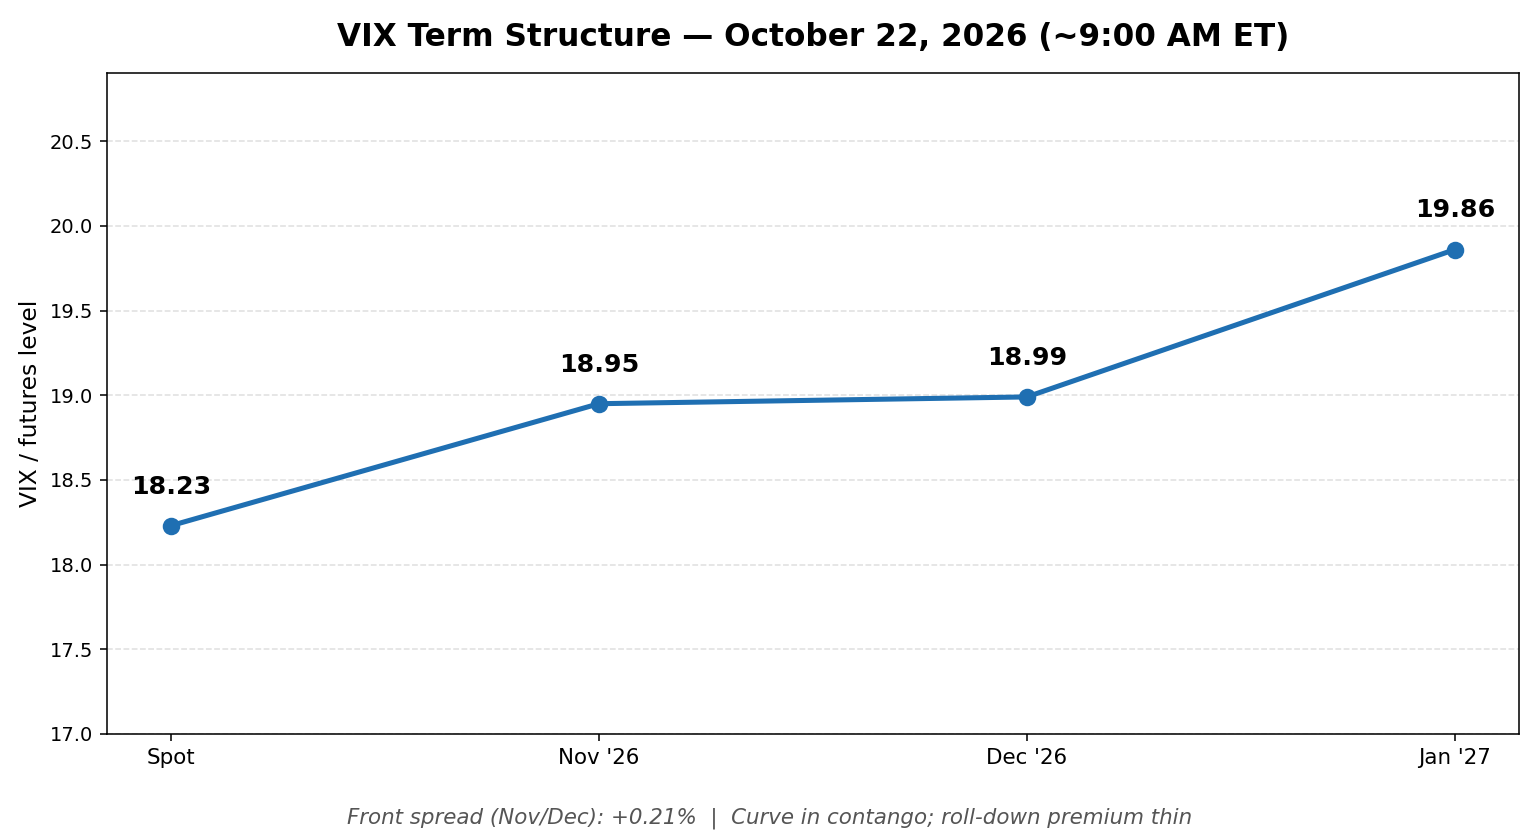
Spot VIX sits near 18.2 this morning, up about 10% overnight. The curve is barely paying for any of it. November futures sit at 18.95, December at 18.99 and January at 19.86, so the spread between November and December is just +0.21%, one of the flattest readings in our running log. There is almost no cushion between spot and the first two contracts, which means an overnight spot shock has very little buffer to lean on. Three months of roll down is worth only about 1.6 points in total, and the first two months contribute almost nothing. The premium on offer for selling volatility is thin just as the calendar gets heavier.
Positioning agrees that hedging is on edge. Dealers finished Wednesday in a negative gamma posture, with the put wall near 7,650, the call wall near 8,100 and the zero-gamma flip at 7,706 against spot near 7,740. In plain terms, spot sits close to the level where dealer hedging flips from damping moves to amplifying them. One model has the flip as low as 7,625, another puts today’s gamma flip at 7,778, so the market is parked inside a dense gamma zone where intraday tape can flip sign quickly. This is the same pinned positioning we have seen all week, now with futures down hard on top of it.
The Fed calendar keeps the December question alive. Initial claims came in at 194,000 versus 200,000 expected, a firm labor input for next week’s FOMC, and futures markets still price roughly a 76% cumulative chance of a quarter-point hike by December. With oil at $112 and inflation back in the tape, a December hike is still very much on the table. The Fed is in its blackout period, so the tape trades on data alone until Chair Warsh speaks Wednesday afternoon. For a December hike to be taken off the table, inflation needs to keep cooling, and the next real test is the September PCE report on October 29, landing the day after the FOMC decision. Note for our readers: Carpenter Technology (CRS), a name on our watchlist, reports its fiscal first quarter before the open today; the Equity Intelligence spotlight remains on hold pending the print.
What changes the read: the curve rebuilding real slope between November and December once this event cluster clears, or a spot VIX that breaks decisively higher and stays there. Until one of those happens, we stay defensive on short volatility: no unhedged short vega, wider wings, and no hurry into FOMC week.
Related: Technicals: Breadth Is Quietly Firming Under a Rising VIX
Educational market analysis only. Not investment advice. See Terms of Use.
Leave a Reply