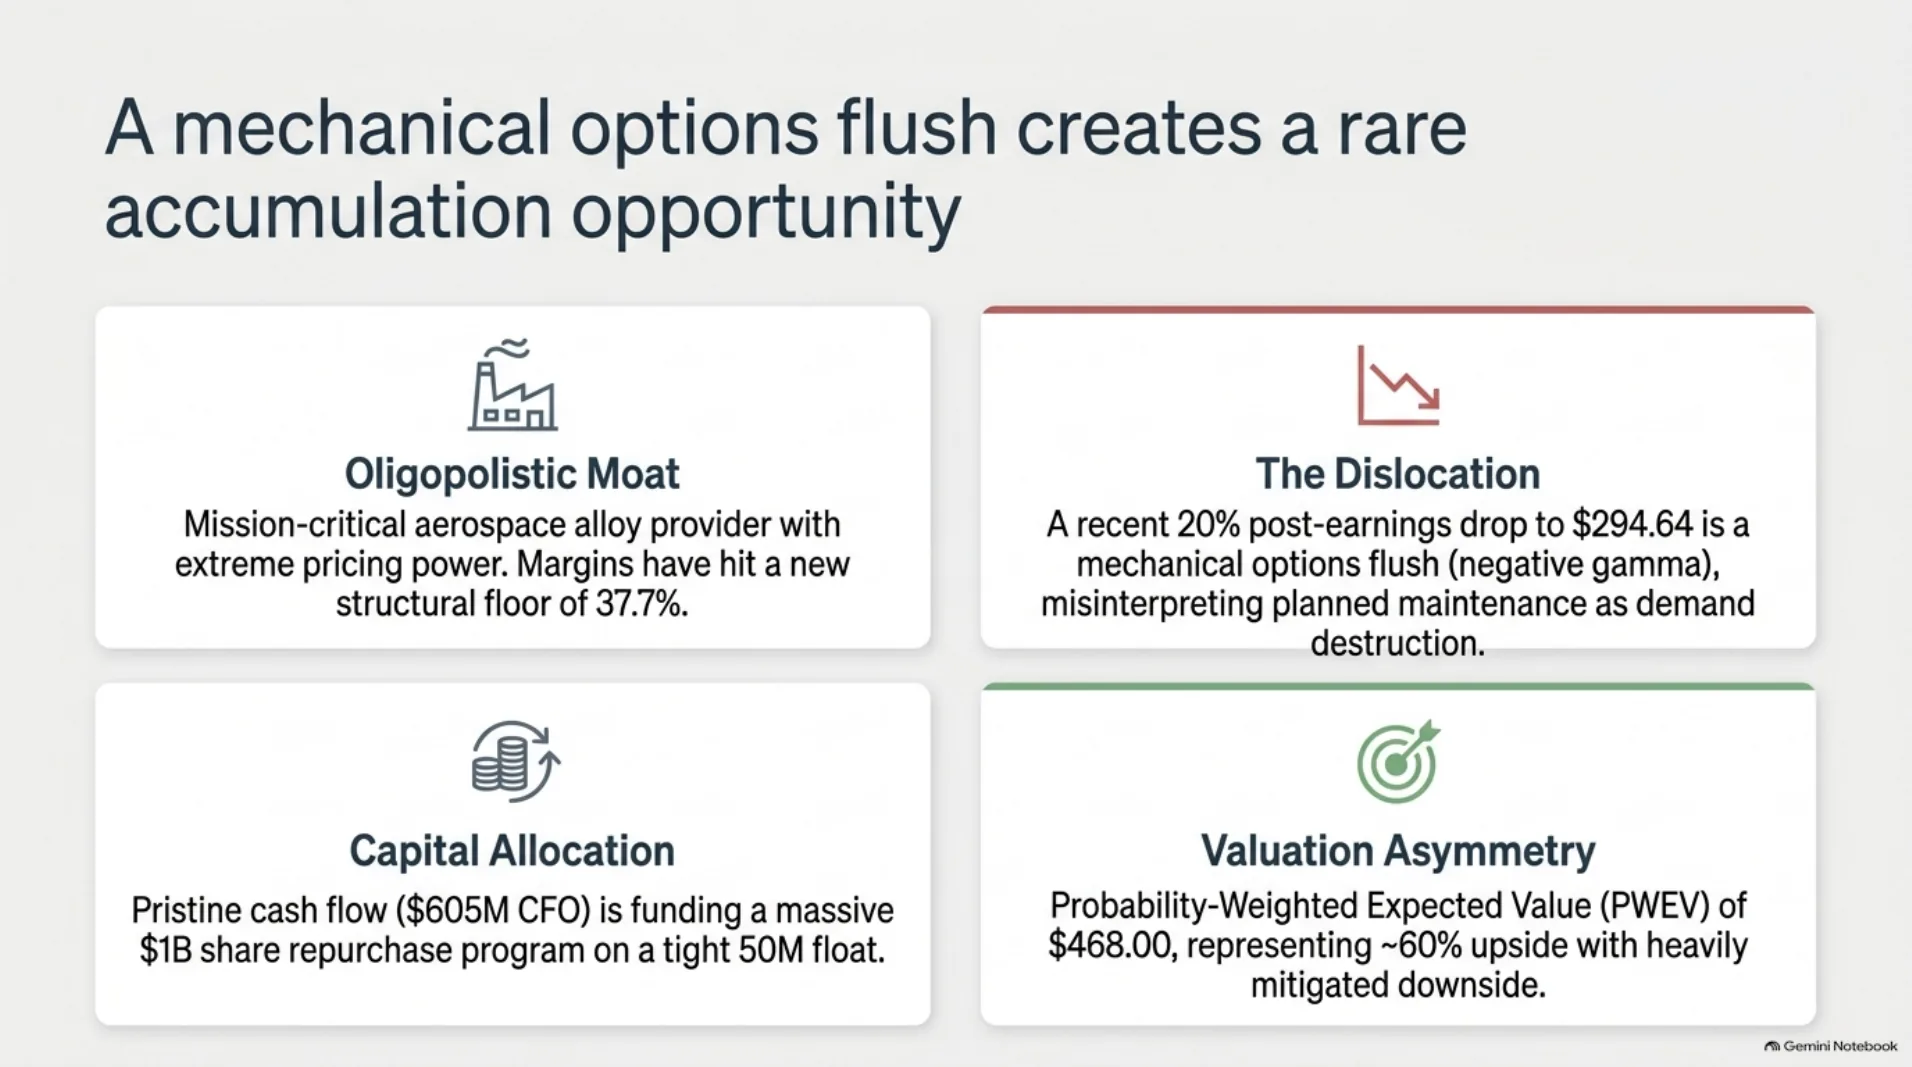
Carpenter Technology (NYSE: CRS) reported fiscal first-quarter results this morning, and the market’s verdict was swift: the stock fell about 20 percent to $294.64. Our verdict, after working through the print and the earnings call, is the opposite. The quarter reaffirms the thesis we laid out in our research, and on net it strengthens it. What the market sold as demand destruction was, on the company’s own explanation, scheduled plant maintenance. The full updated slide deck follows this summary, and a PDF version is available for download at the end.
What the quarter actually showed
- GAAP EPS of $3.25 beat the $3.04 consensus
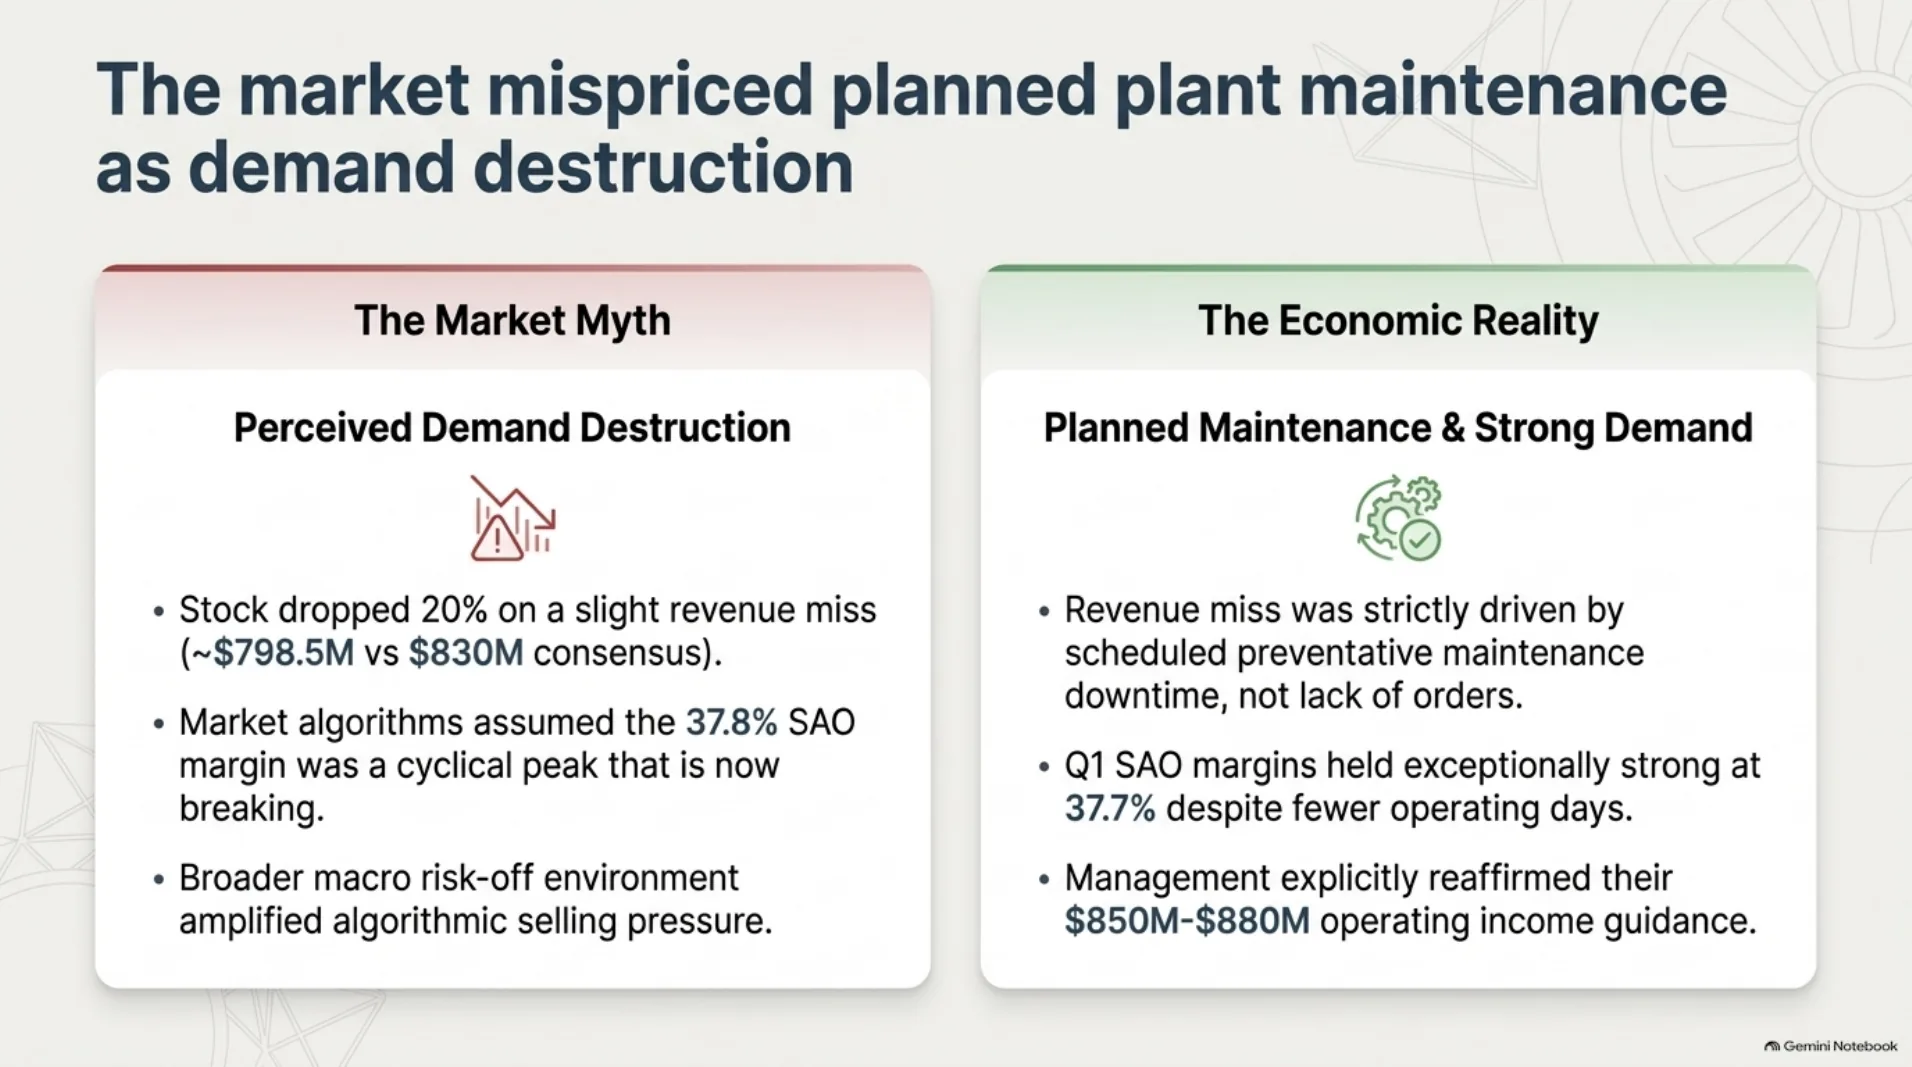
- Revenue of $798.2 million missed the roughly $830 million consensus, and management attributed the shortfall strictly to scheduled preventative maintenance downtime, not to orders
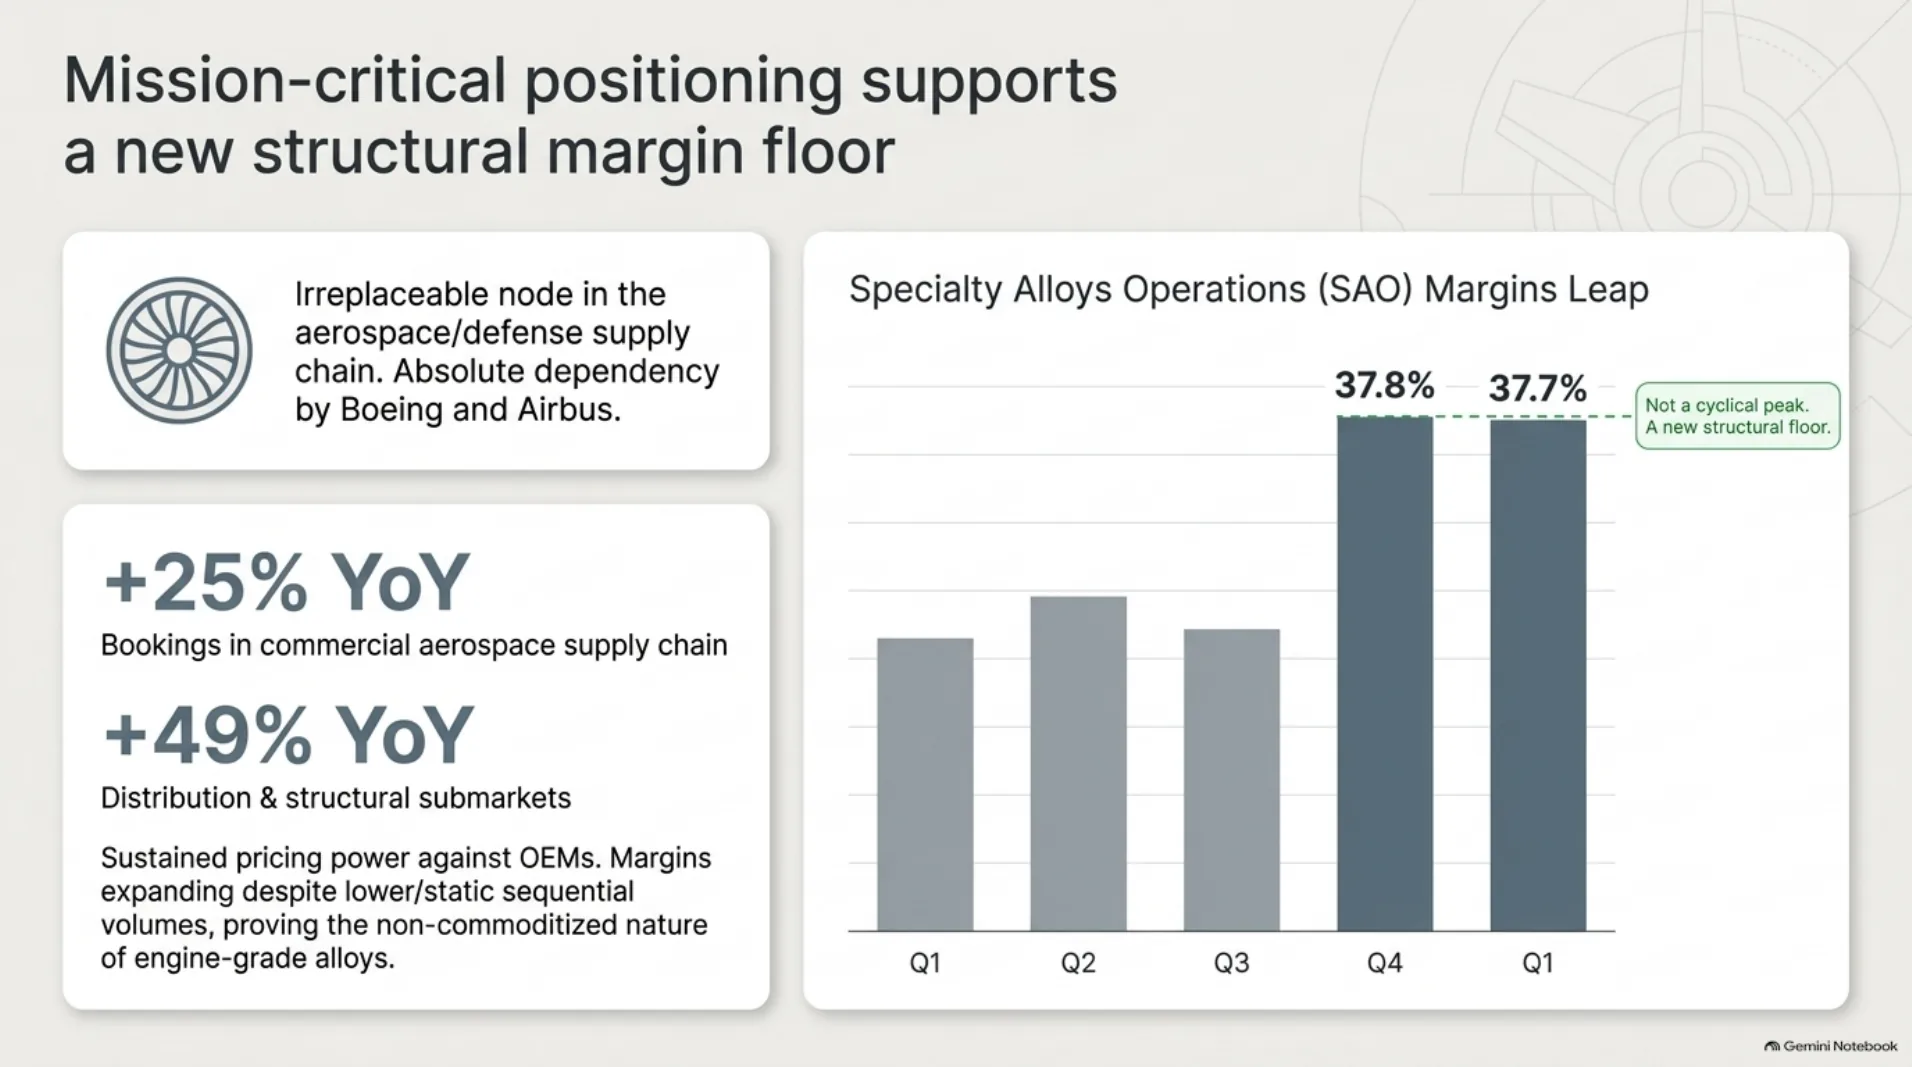
- SAO segment margin held at 37.7 percent, essentially matching last quarter’s record 37.8 percent, despite fewer operating days. The structural floor held exactly where the thesis needed it to
- Fiscal 2027 operating income guidance was explicitly reaffirmed at $850 million to $880 million; the softer second quarter guide of $192 million to $197 million reflects the same maintenance timing, pushing delivery into the back half rather than removing it
- Bookings tell the demand story directly: commercial aerospace bookings up 25 percent year over year, distribution and structural submarkets up 49 percent
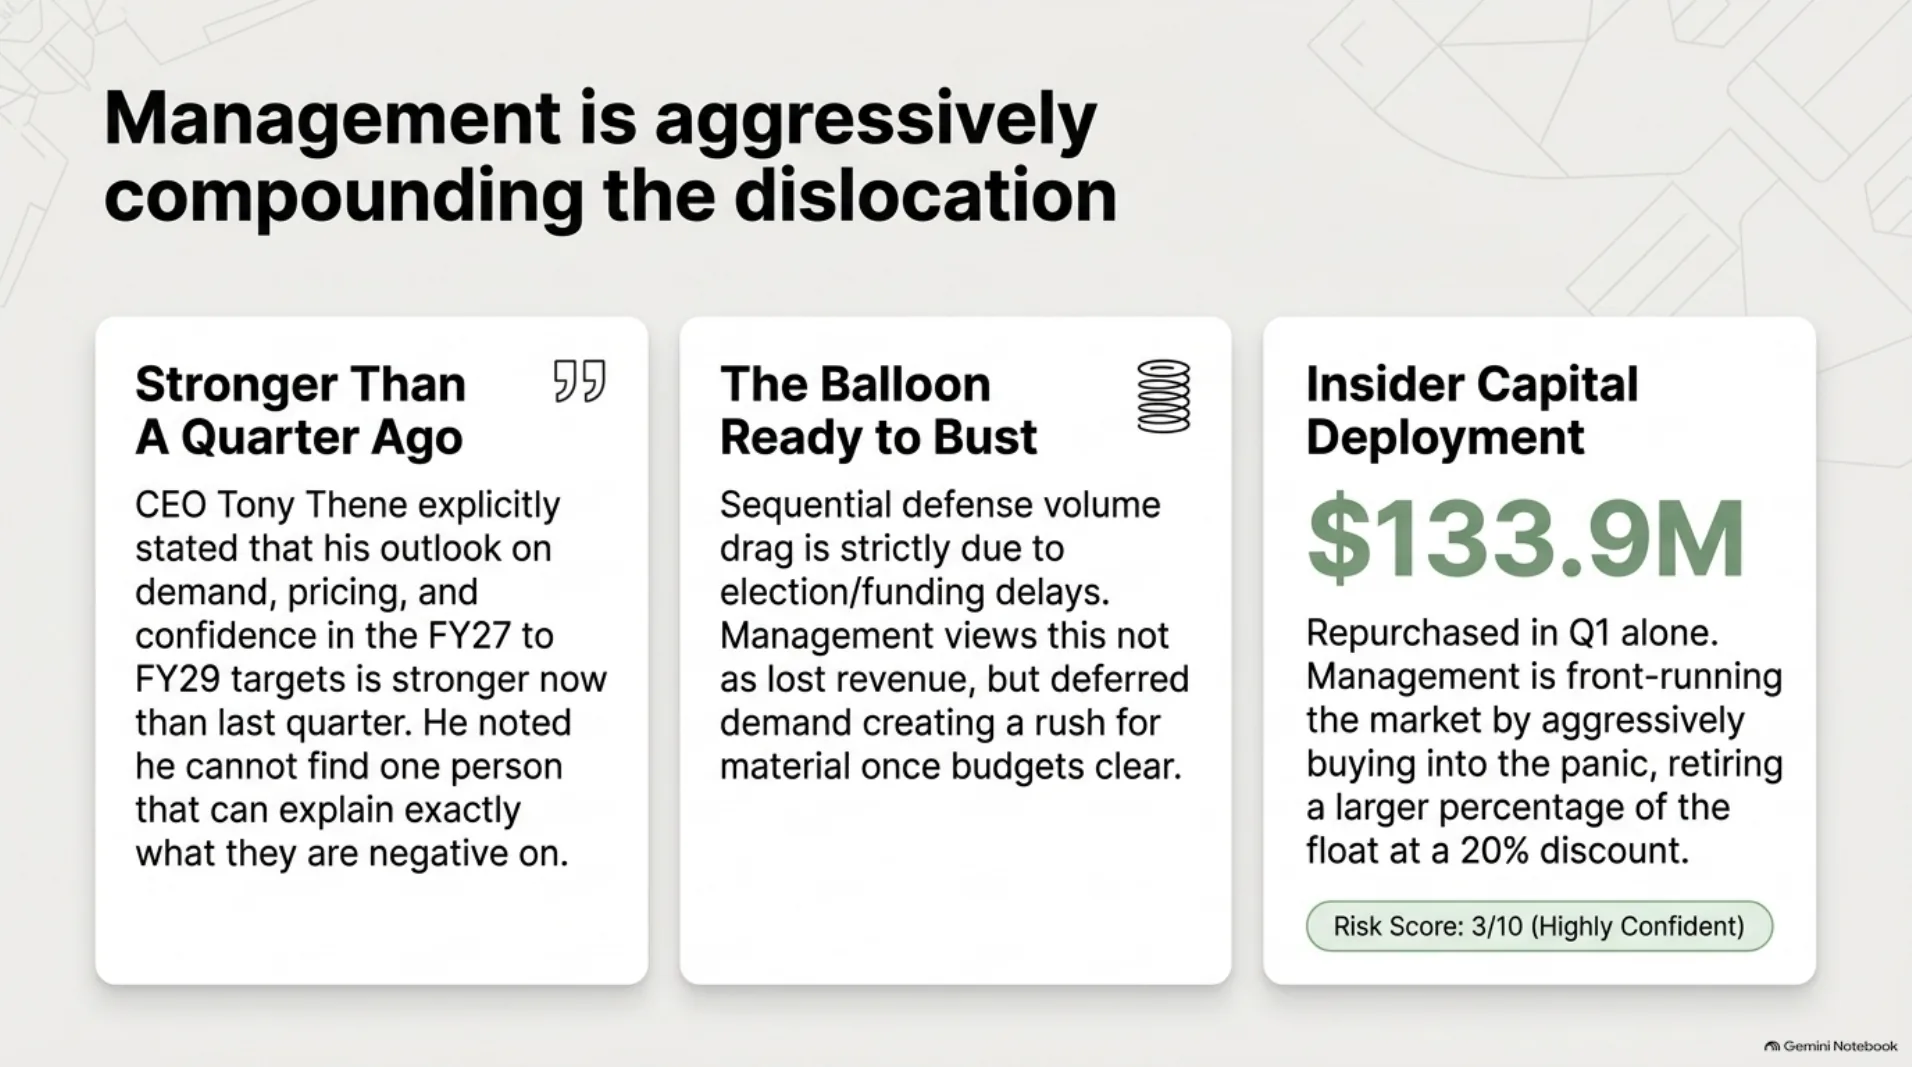
- The sequential defense volume drag is, in management’s framing, election and funding delays: deferred demand, not lost demand
- CEO Tony Thene said his confidence in the fiscal 2027 to 2029 targets is stronger than it was a quarter ago
- The company repurchased $133.9 million of stock in the first quarter alone
Why the stock fell 20 percent anyway
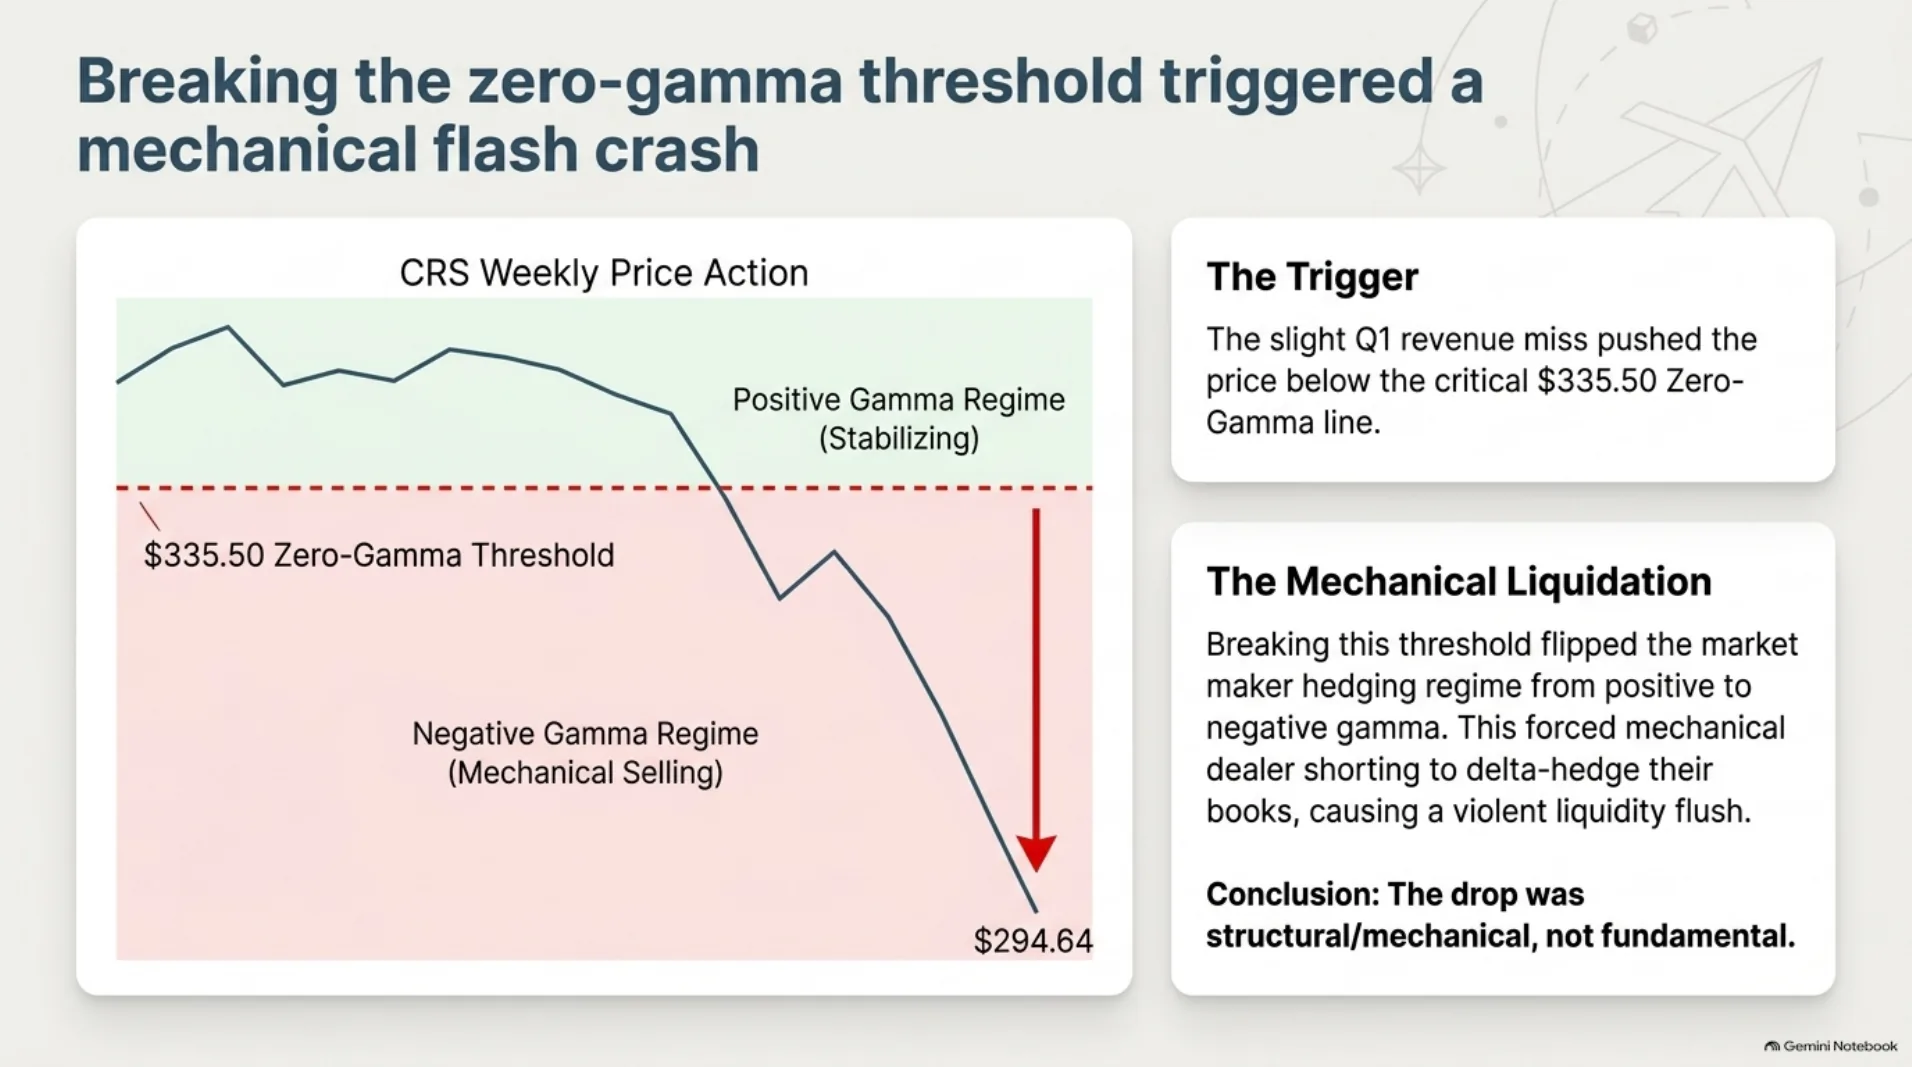
The mechanics matter here. The revenue miss headline pushed the price through the $335.50 zero-gamma level, the line where dealer hedging flips from stabilizing to amplifying moves. Below it, market makers hedge by selling into declines, and in a broadly risk-off tape that mechanical selling turned a modest headline miss into a liquidity flush. Nothing in that chain is a fundamental judgment about Carpenter’s order book, margins, or cash flow. It is positioning math, and it is the same math that creates the entry.
The thesis, updated
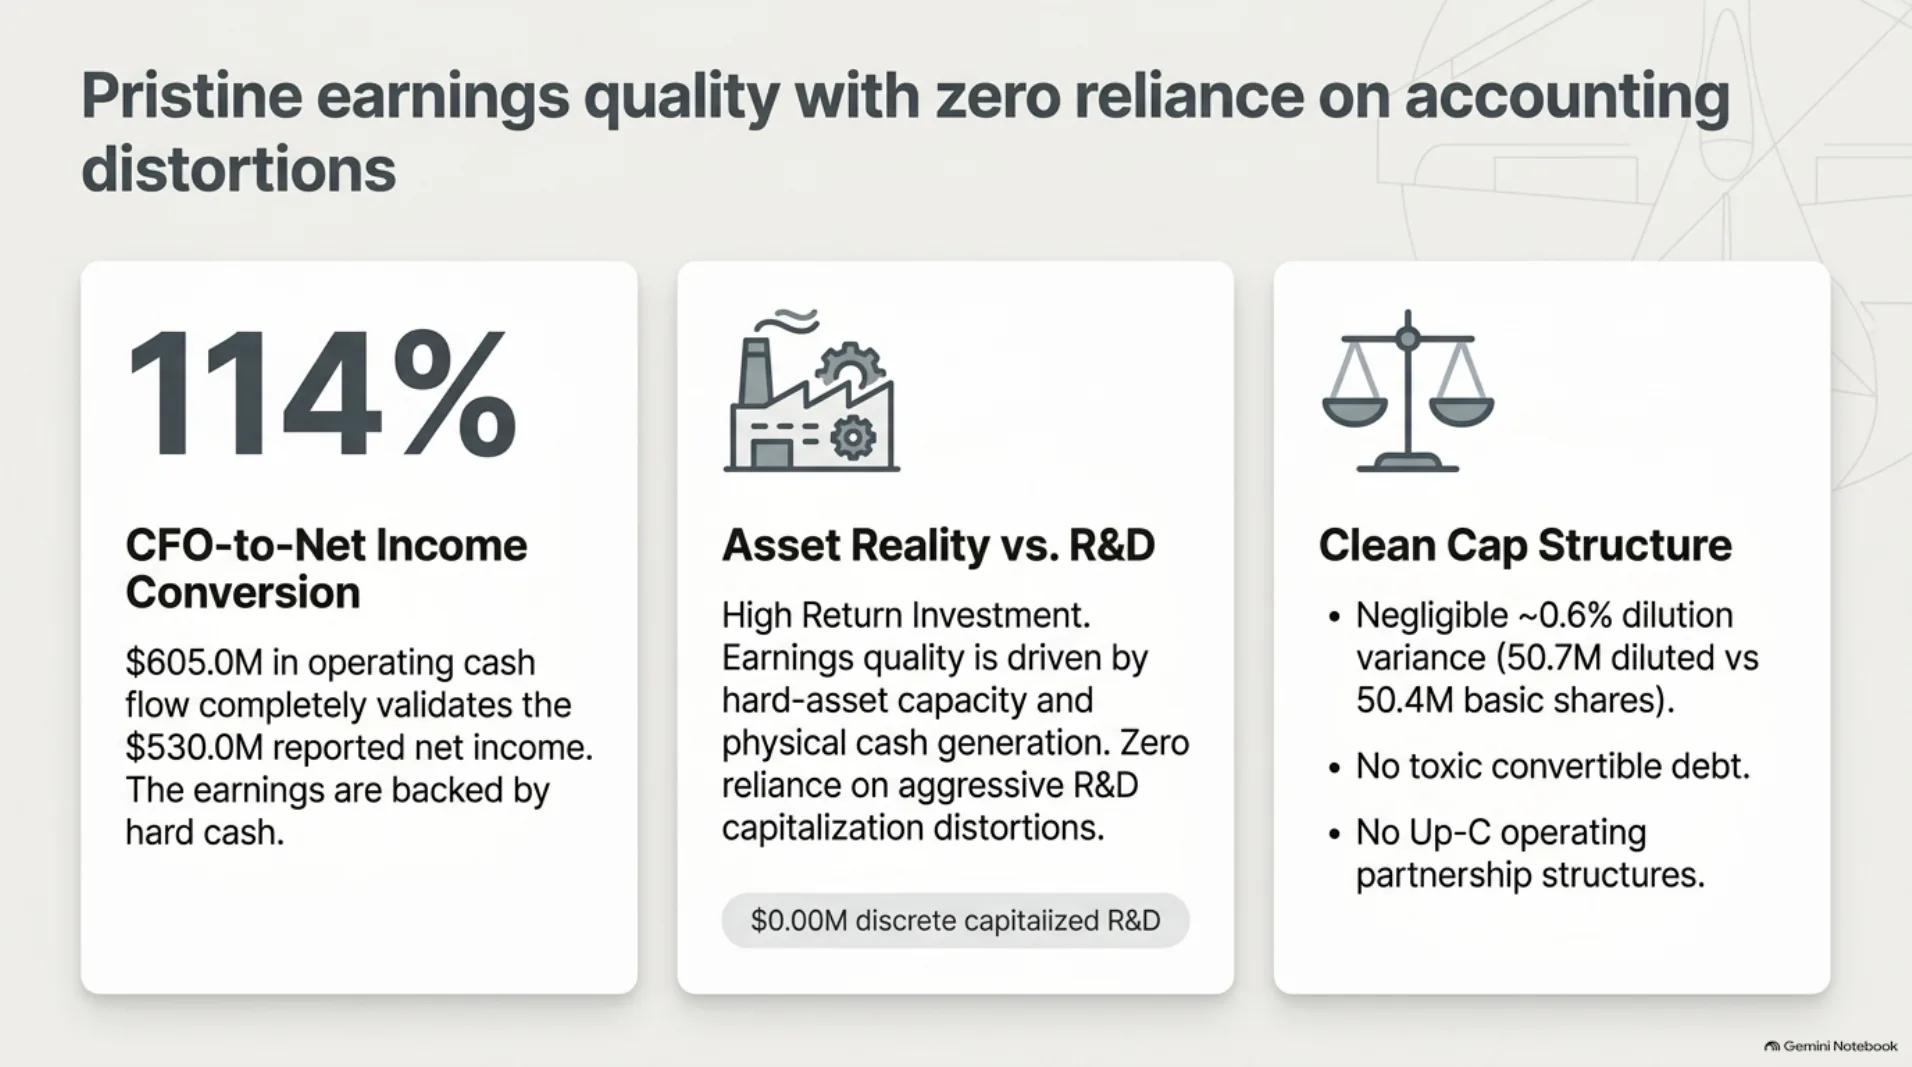
The market prices Carpenter as a late-cycle materials company at a cyclical peak. Our read remains different. Carpenter is an oligopolistic supplier of mission-critical aerospace alloys with near-monopolistic pricing power, and a 37.7 percent SAO margin printed in a maintenance-reduced quarter is evidence of a structural floor, not a peak. Earnings quality stays pristine: $605 million of operating cash flow, a 114 percent conversion of net income, $892.4 million of liquidity, no capitalized R&D distortions, and a clean capital structure with diluted shares only about 0.6 percent above basic.
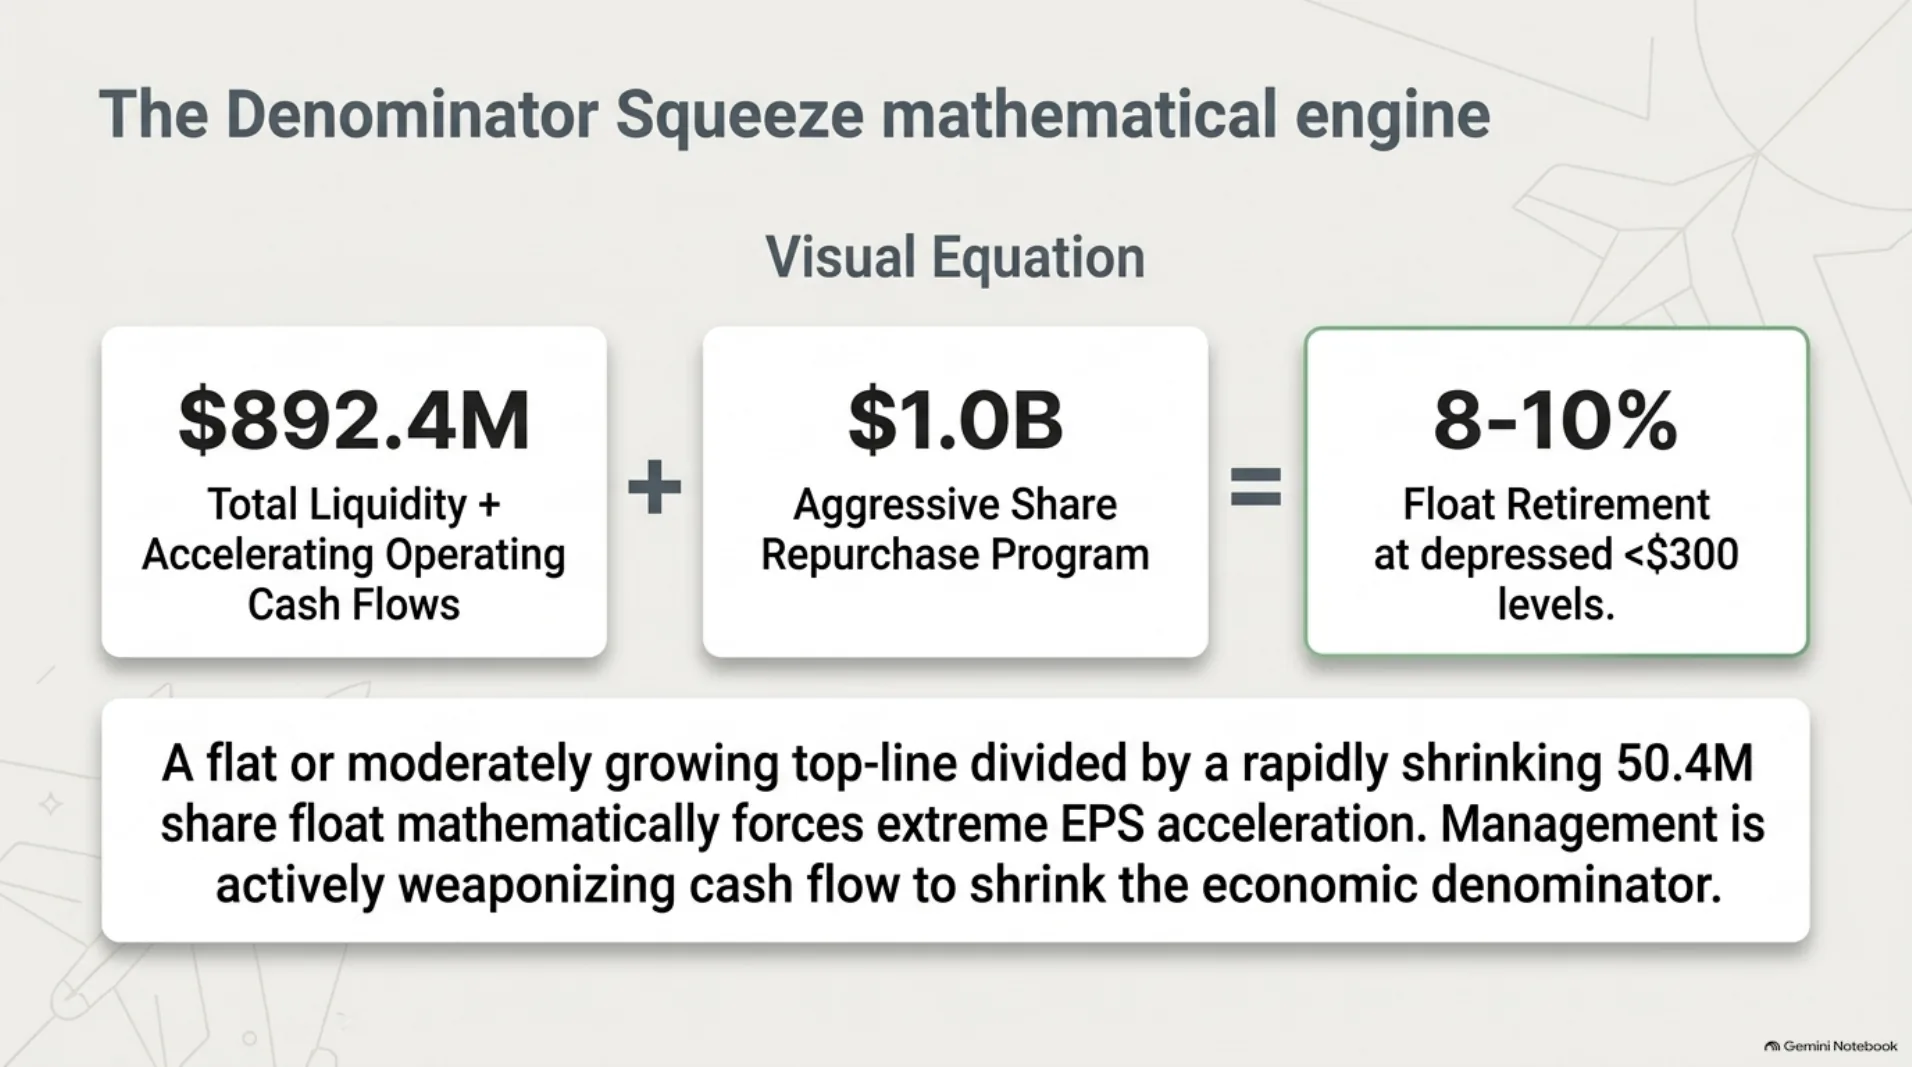
Layered on top is the denominator squeeze. The $1.0 billion repurchase program, $133.9 million of it already executed in the first quarter, works against a tight 50.4 million share float and implies an estimated 8 to 10 percent float retirement, executed now at prices under $300. A flat to moderately growing top line divided by a rapidly shrinking share count forces EPS acceleration arithmetically. Management is, in effect, front-running its own undervaluation, and buying the panic at a 20 percent discount.
Valuation: three scenarios, unchanged framework
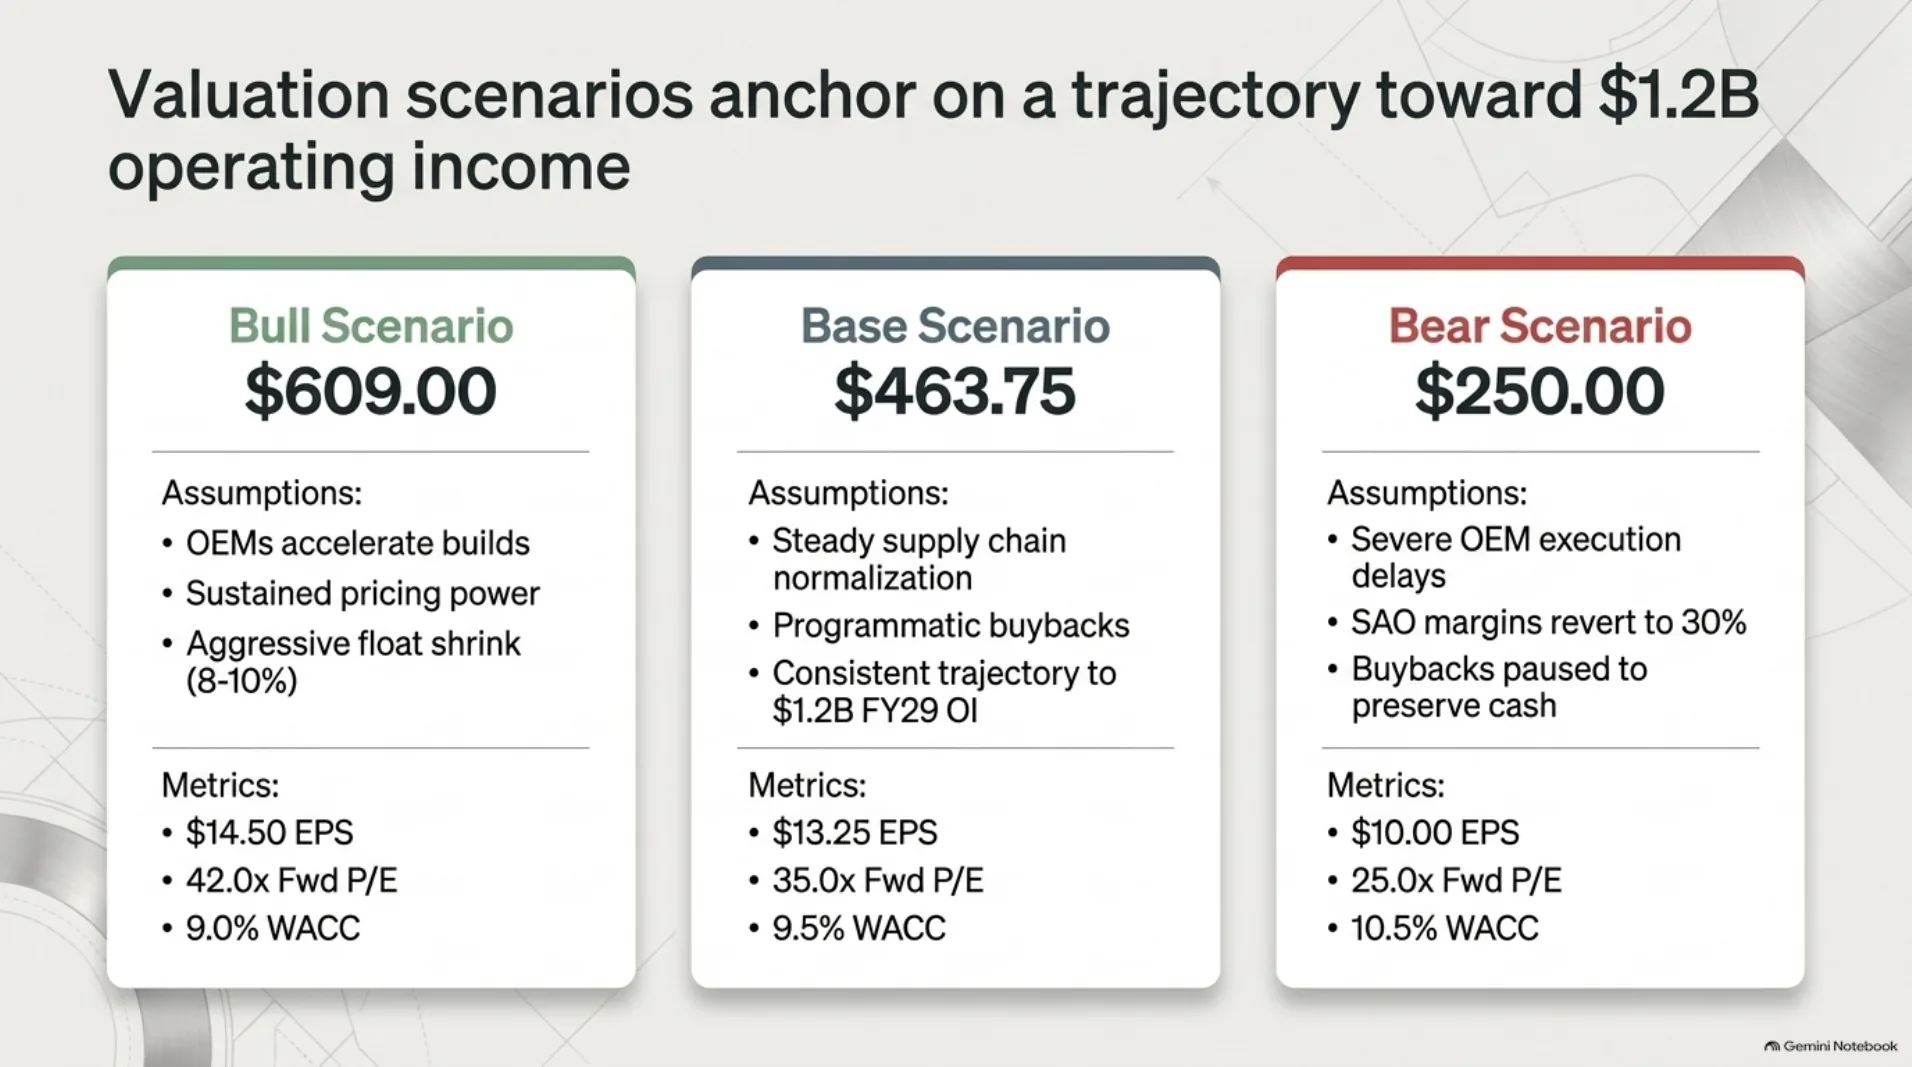
- Bull (25% weight): OEMs accelerate builds, pricing power sustained, float shrinks 8 to 10 percent, target $609.00
- Base (60% weight): steady supply chain normalization, programmatic buybacks, trajectory toward $1.2 billion of fiscal 2029 operating income, target $463.75
- Bear (15% weight): severe OEM execution delays, SAO margins revert to 30 percent, buybacks paused, target $250.00
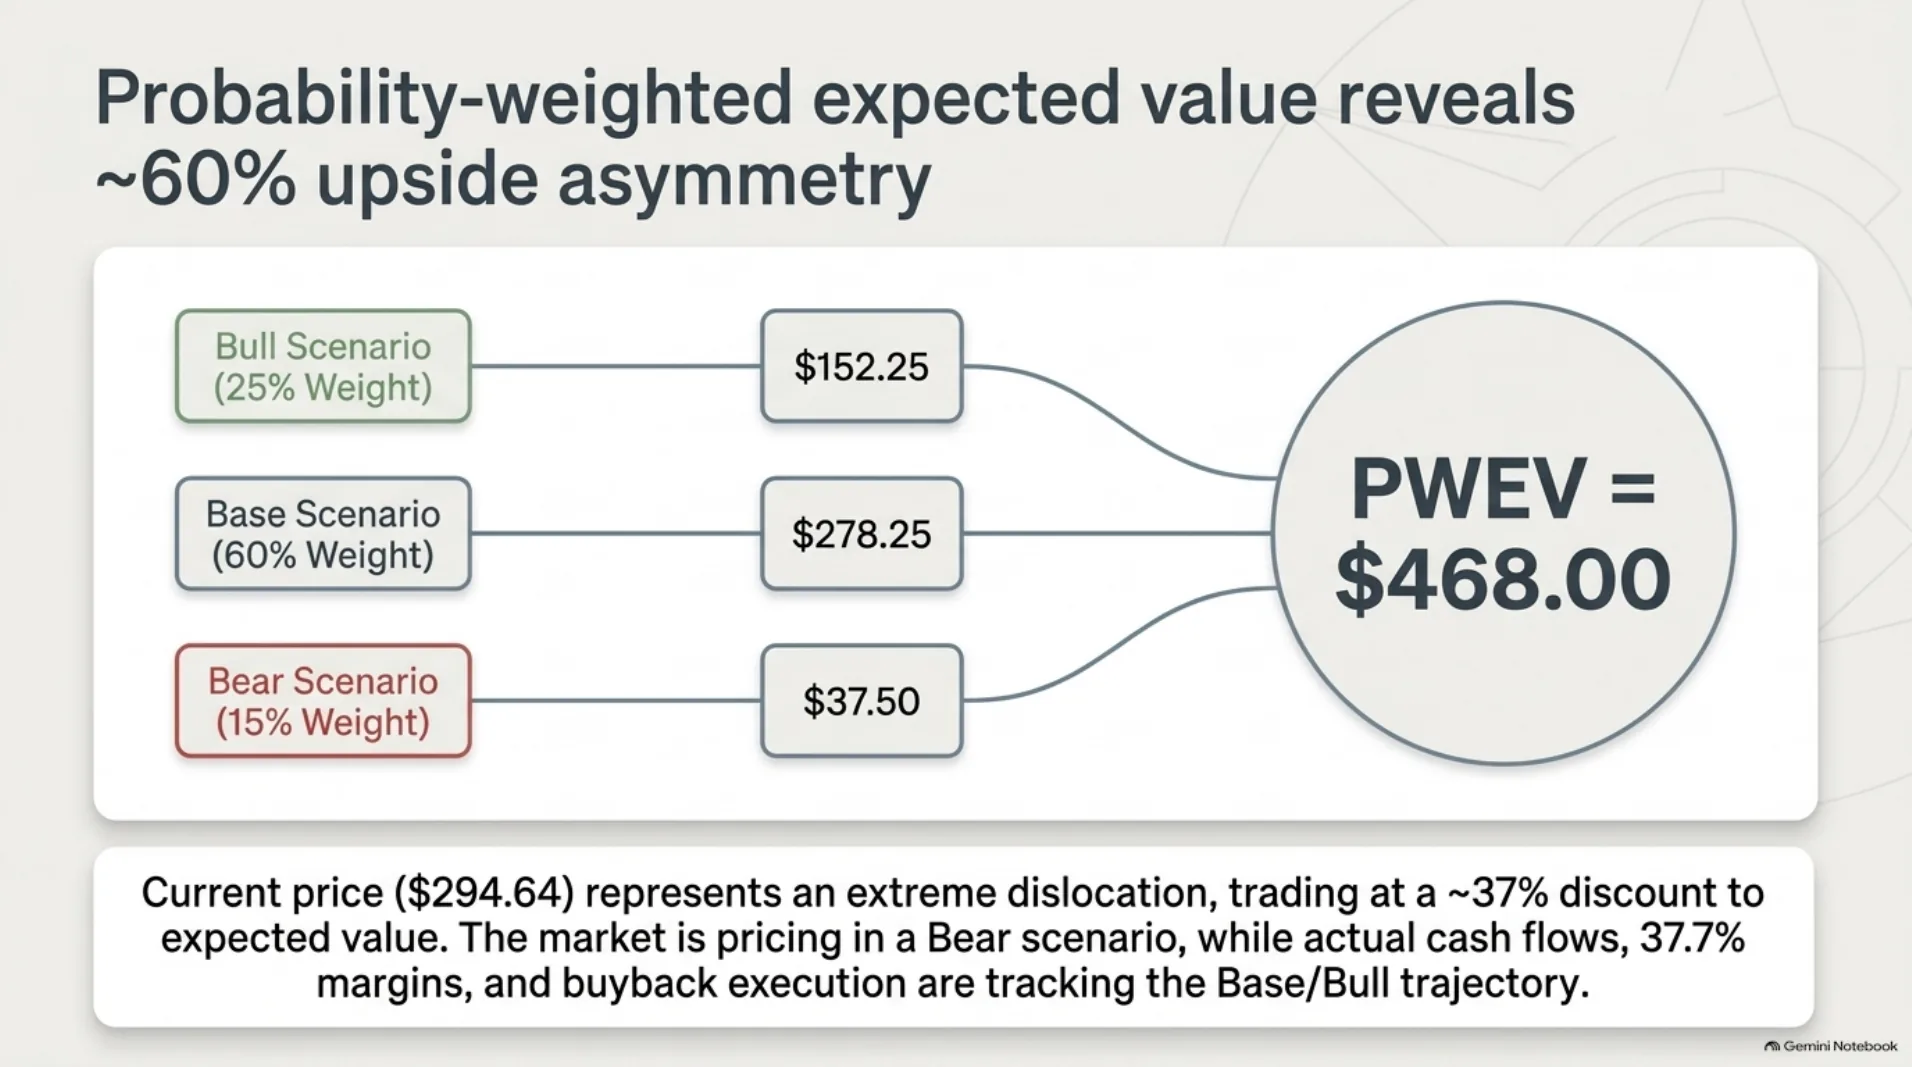
Probability-weighted, the framework still produces a $468.00 expected value. What changed is the entry: at $294.64 the stock trades at roughly a 37 percent discount to that expected value, about 59 percent of upside, priced as though the bear scenario were already the base case while margins, cash flow, and buyback execution track the base-to-bull path.
The tactical pivot
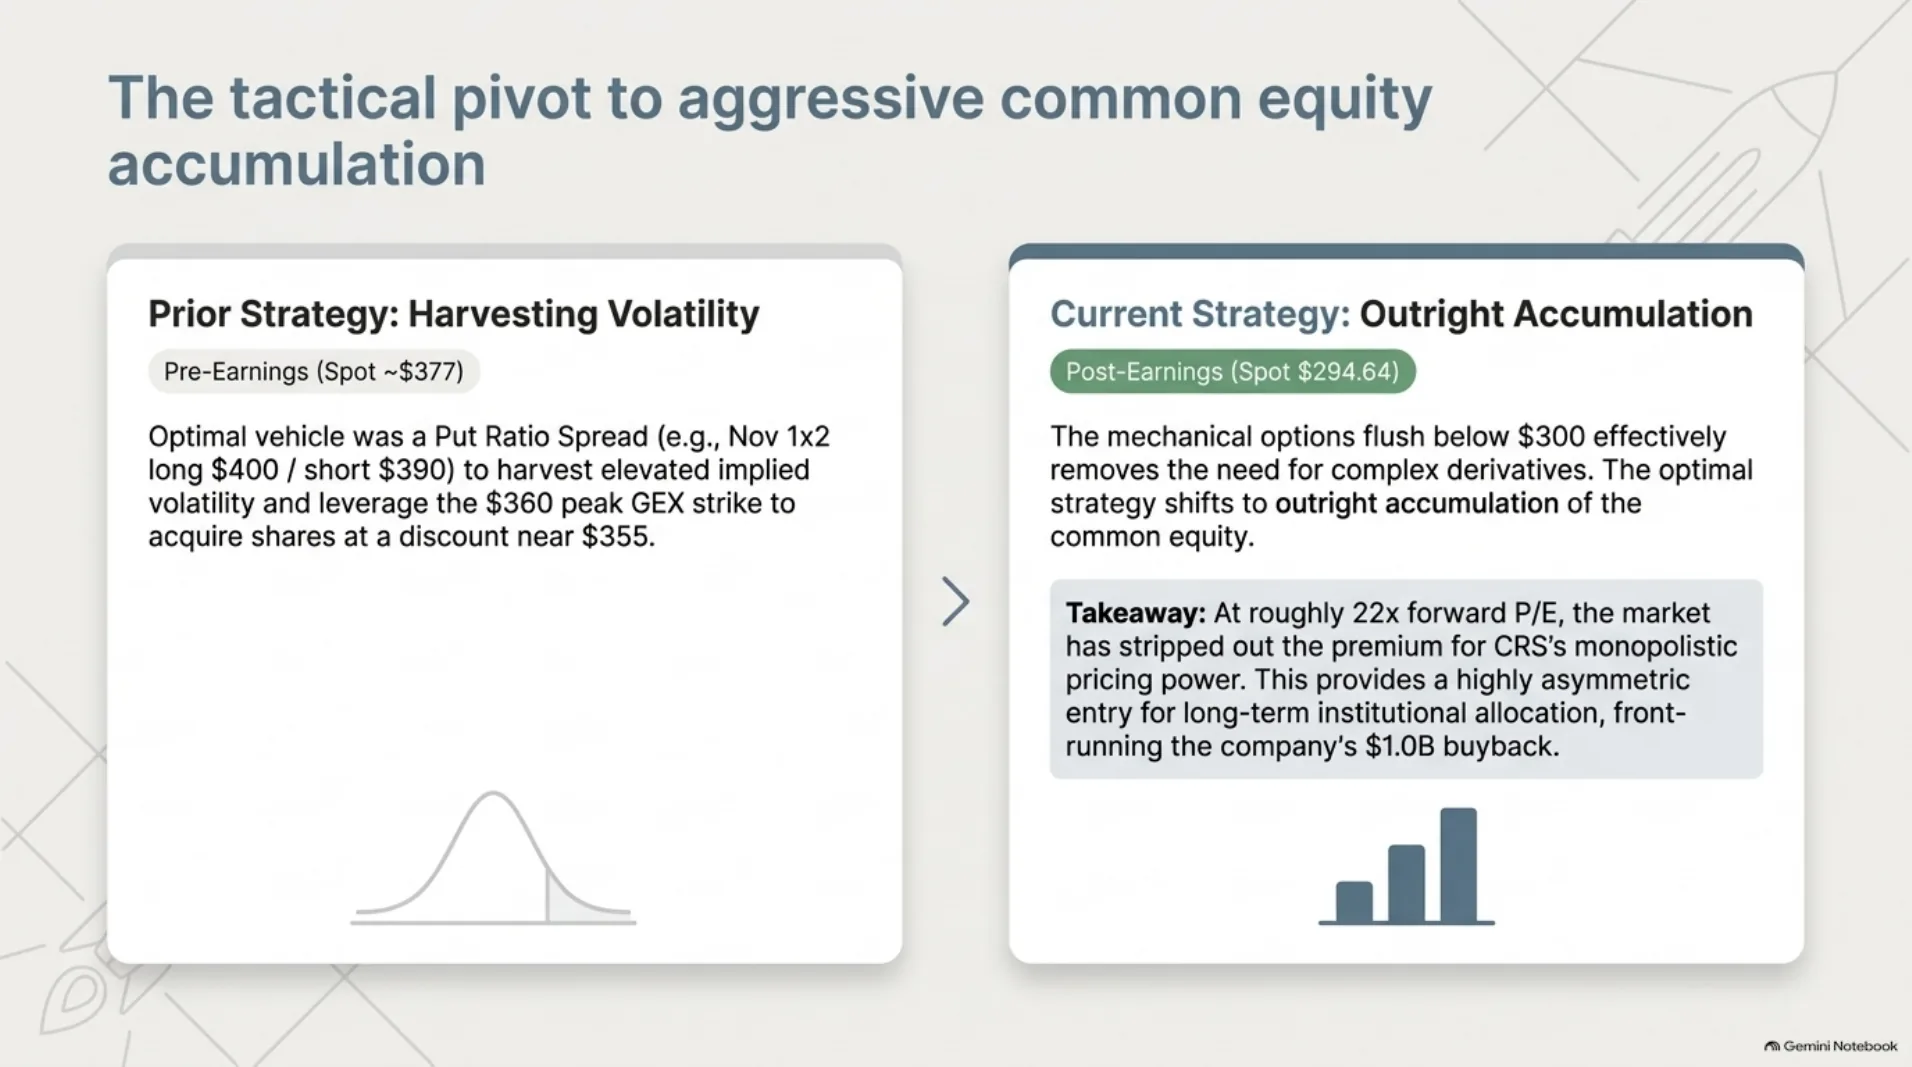
Before earnings, with the stock near $377, our preferred expression was a November put ratio spread, harvesting elevated implied volatility with an effective assignment basis near $355. The flush below $300 removes the need for the structure. At roughly 22 times forward earnings, the market has stripped out the premium for Carpenter’s pricing power, and the cleaner trade is outright accumulation of the common equity, ahead of the company’s own $1.0 billion bid.
What would change our mind
- Fiscal 2027 guidance actually cut, rather than reaffirmed against maintenance timing
- SAO margin reverting toward 30 percent, which would prove the peak-margin bears right
- The buyback paused or slowed materially while the stock sits at these levels
- Boeing or Airbus build-rate problems that cap volumes regardless of pricing power
One caveat: while the price sits below the zero-gamma line, positioning stays unstable and the stock can overshoot in either direction. That is a sizing consideration, not a thesis problem.
The full deck
Disclosure: John Lah does not hold a position in Carpenter Technology (CRS) at the time of publication and may purchase shares following publication.
Educational market analysis only. Not investment advice. See Terms of Use.
Leave a Reply