Housing starts came in at 1.221 million against a 1.30 million consensus, a 5.2% monthly drop, with the prior month revised down on top of it. At 7.5% mortgage rates, construction is finally bending. This is the first real soft-demand print of the month, and it lands against a run of inflation data that has done nothing but surprise hot.
Today’s scorecard:
| Release | Actual | Consensus | Prior | Verdict |
|---|---|---|---|---|
| Housing Starts (Sep) | 1.221M | 1.30M | 1.288M | NEGATIVE |
| Building Permits (Sep) | 1.400M | 1.39M | 1.403M | IN-LINE |
| ADP Employment, weekly | 18.5K | n/a | 24.75K | NEGATIVE |
Permits, the forward-looking piece, were basically flat: a tiny beat versus consensus, down from the prior month. The pipeline isn’t growing, it just isn’t collapsing. The weekly ADP number, experimental as it is, pointed the same direction as housing: softer.
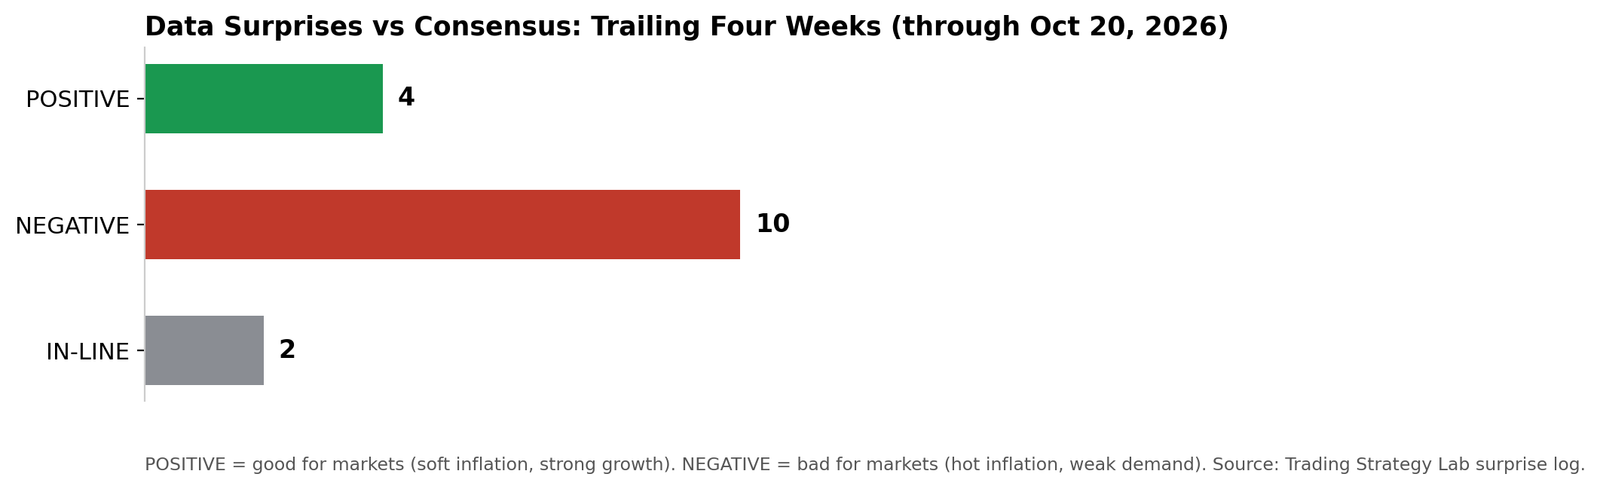
The surprise trend: today adds 0 POSITIVE, 2 NEGATIVE, 1 IN-LINE to the running scorecard. Over the trailing four weeks the tally is 4 POSITIVE, 10 NEGATIVE, 2 IN-LINE, which in plain terms means the data has been running hotter than expected all month. Today’s housing miss is the first crack in that pattern, and it is a demand crack, not an inflation relief print. Those are not the same thing.
The Fed path: the October 27-28 meeting is effectively settled, priced at roughly 85-87% for a hold, with the Fed in blackout. December is the live meeting, and it blinked: hike odds fell to about 78%, down from roughly 92% yesterday. One soft housing number gives the wait-and-see camp ammunition, but it does not outweigh a month of hot CPI and PPI. For a December hike to be taken off the table, inflation needs to keep cooling. Housing alone won’t do that job.
Nowcasts: Atlanta Fed GDPNow has Q3 growth at 3.6% annualized, with today’s update still to come (the starts miss nudges residential investment lower). The Cleveland Fed’s October inflation nowcast sits near 3.8% year over year on headline and 2.5% on core. Growth fine, inflation still hot. That is the whole tension in two numbers.
What changes the read: tomorrow’s initial jobless claims. Above roughly 210K and the softness is spreading from housing into layoffs, which would pressure December pricing further. A soft print near 195K and the wait-and-see camp keeps December in hand. Pending home sales at 10 AM today is the appetizer.
Educational market analysis only. Not investment advice. See Terms of Use.
Leave a Reply