The fear gauge keeps cooling and the curve keeps refusing to pay for it. Our regime read stays AMBER, continue defensive posture.
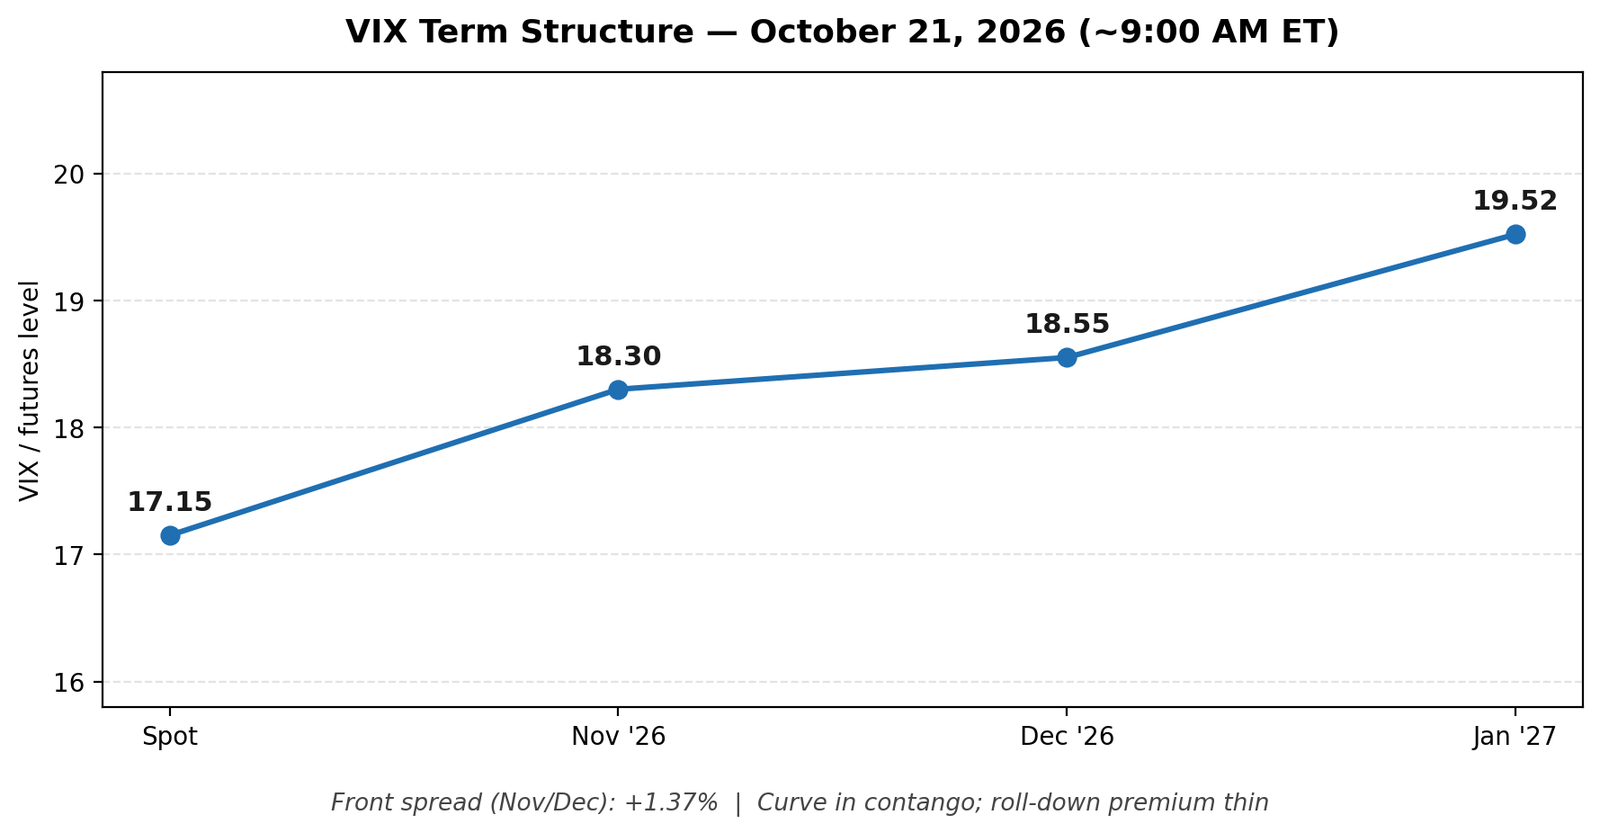
Spot VIX sits at 17.15 this morning, its calmest level in weeks, and the October futures contract expired with the open, which hands the front of the curve to November. November futures sit at 18.30 and December at 18.55, so the front spread has narrowed again, to just +1.37% from +2.70% two days ago. There is even less slope here than yesterday, and even less roll-down income for short-volatility structures. The premium on offer keeps shrinking while the calendar underneath it keeps getting heavier.
Positioning has not changed its mind either. Dealers finished Tuesday still slightly net short gamma, with the put wall and call wall both sitting practically on top of the market near 7,710 to 7,715 and the gamma flip above at 7,775. In plain terms, the market is pinned near the level where dealer hedging starts amplifying moves instead of damping them. Tuesday’s session itself was constructive, the S&P 500 closed up 0.28% at 7,712.57 and back above its 50-day average, led by breadth rather than the biggest names, but one good rotation day does not clear the positioning.
December pricing swung back the other way. Yesterday we noted December hike odds had blinked down to about 78% on the soft housing print. With oil flirting with $100 and the inflation scare back in the tape, futures markets have re-priced the December hike to roughly 89%. The direction of travel matters: one soft housing number did not take a December hike any closer to being taken off the table. For a December hike to be taken off the table, inflation needs to keep cooling, and the next real test is the September PCE report on October 29, awkwardly landing the day after the FOMC decision.
Earnings are the other weight on this week. Tesla, Meta, IBM, Lam Research, and Texas Instruments all report tonight, and the deluge continues through the rest of the week. Netflix set the tone early: a beat on the numbers, a weak revenue guide, and a 6.6% premarket drop. In this stretch, guidance is the bar, not the print. Stacked earnings on top of next week’s FOMC, the PCE and GDP reports, and the November 3 midterms is exactly the kind of cluster where thin volatility premium is a warning, not an invitation.
What changes the read: the spread between the front two contracts rebuilding real slope once the event cluster clears, or a spot VIX that stops respecting the high teens. Until one of those happens, we stay defensive on short volatility: no unhedged short vega, wider wings, and no hurry.
Educational market analysis only. Not investment advice. See Terms of Use.
Leave a Reply